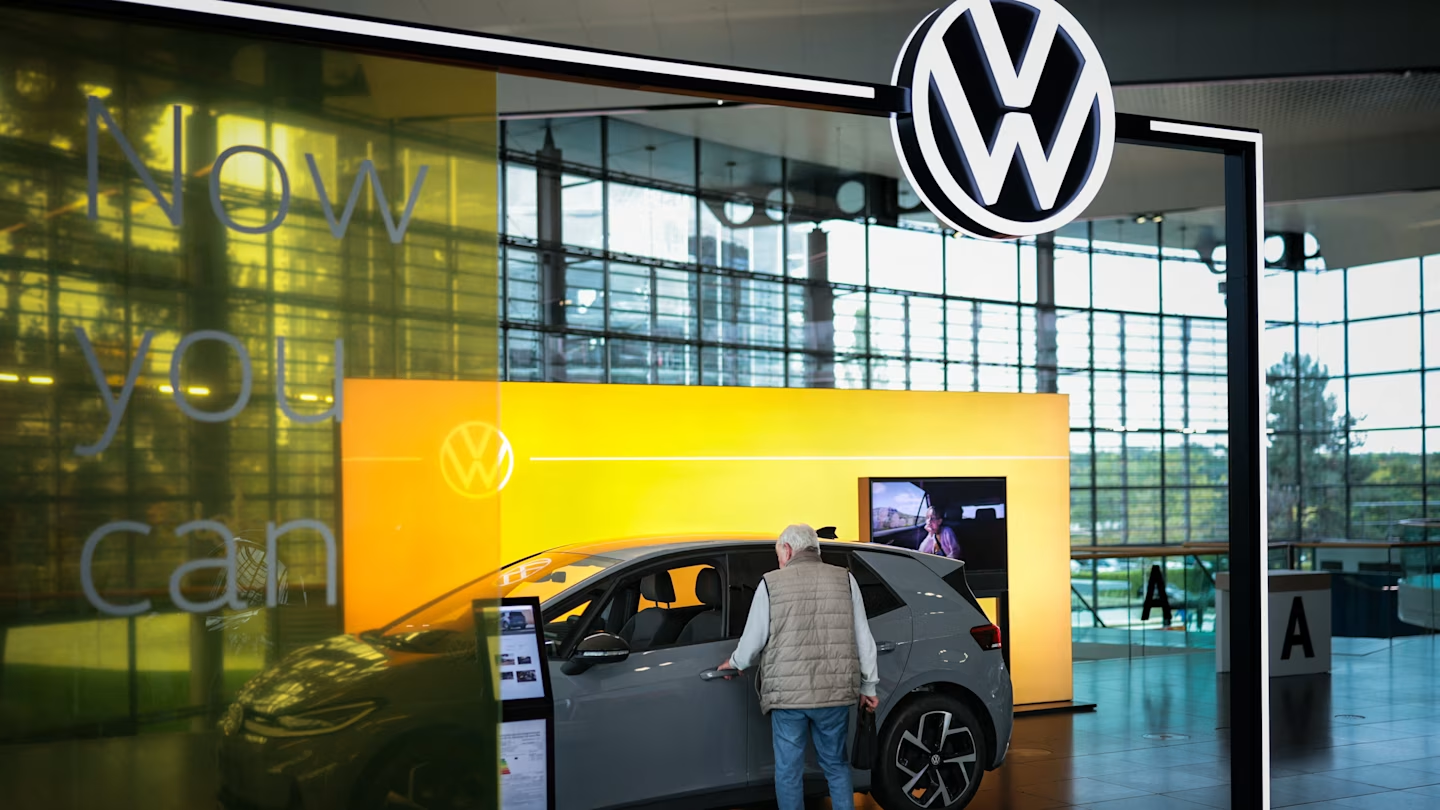
- Volkswagen dropped from Euro Stoxx 50 index for first time in 15 years after shares fell to 16-year low (down 75%+ from 2021 peak). Removal likely to trigger selling from €59bn in 30 ETFs tracking index, exacerbating share price pressure. VW’s market cap of €38bn vs €322bn annual sales reflects extreme investor skepticism about restructuring costs and competitive position. €6bn writedown on Porsche stake, plummeting China sales, US tariff pressures, and €100,000 job cut restructuring drive valuation collapse. Traders expect index removal to create additional downward spiral.
- VW’s removal follows Stellantis (Fiat/Peugeot maker) ejection last year; Stellantis share price nearly halved since removal despite company undergoing leadership reshuffle. Cautionary tale validates that index removal triggers mechanical selling beyond fundamental deterioration. VW insists restructuring will improve financial performance and enable “return to Euro Stoxx 50 in medium term.” Only three car stocks remain in Euro Stoxx 50: Ferrari (luxury positioning protects from mass-market Chinese competition), BMW, Mercedes-Benz. Removal highlights automotive sector’s “seemingly existential risks” from Chinese rivals and EV transition costs.
- Index reconstitution validates sector rotation: VW/Wolters Kluwer exiting; Nokia (network provider for AI data centres, backed by Nvidia) and Engie (French utility benefiting from energy transition) entering. Rotation reflects market recognition that legacy European industrial base faces structural challenges while AI infrastructure/energy transition offer growth. German blue-chips in Euro Stoxx 50 declining to 16; German sub-index underperformed broader Euro Stoxx 50 (10.9% annualized return vs 12.5% for whole index over past 5 years).
- VW’s governance complexity (family voting control, Porsche stake complexity) seen as hampering transformation needed to compete with Chinese EV makers. Market valuation sends “very clear signal about just how sceptical investors are about Volkswagen” per asset manager. Despite August union deal and 9% stock rebound, September profit warning and 8.3% drop underscore persistent doubts. Rival auto executive called removal “sign of the times”—reputational impact likely bigger than actual investment outflows. German industrial decline validated by persistent underperformance of German stocks in Eurozone’s most important index.
What Happened?
Volkswagen removed from Euro Stoxx 50 for first time in 15 years after shares fell to 16-year low. VW shares down 75%+ from 2021 peak; current market cap €38B vs €322B annual sales. Removal likely triggers selling from €59B in 30 ETFs tracking index plus 110,000+ structured products tied to index. VW cited €6B Porsche stake writedown, China sales decline, US tariff pressures, and €100,000 job cut restructuring as headwinds. Simultaneously, Nokia (data centre network provider, Nvidia-backed) and Engie (French utility) entering index; Wolters Kluwer also exiting. Only three car stocks remain in Euro Stoxx 50: Ferrari, BMW, Mercedes-Benz. German blue-chips declining in index; German sub-index underperformed 10.9% annualized vs 12.5% for whole Euro Stoxx 50 over past 5 years.
Why It Matters?
For Volkswagen shareholders, index removal triggers mechanical selling from €59B in ETFs and 110,000+ structured products, exacerbating downside pressure. For BMW/Mercedes shareholders, VW removal highlights automotive sector’s existential challenges despite their relative strength remaining in index. For Stellantis shareholders, VW removal validates concern that index removal creates negative spiral (Stellantis nearly halved since 2023 removal). For Nokia shareholders, entry to Euro Stoxx 50 validates company’s reinvention as AI infrastructure beneficiary. For Engie shareholders, entry validates energy transition growth narrative. For German investors, removal reflects persistent underperformance of German blue-chips vs Eurozone—structural competitiveness concern.
What’s Next?
Monitor VW share price in coming weeks; if removal triggers cascading ETF selling, further downside likely. Watch for other automotive sector stocks at risk of removal (BMW/Mercedes if they weaken further). Track VW’s restructuring execution; if €100,000 job cuts proceed smoothly and Porsche stake stabilizes, it could support valuation recovery and index re-entry. Monitor Chinese EV competition; if VW’s China sales continue declining despite restructuring, it validates investor skepticism. Track Nokia/Engie stock performance post-entry; if both outperform, it validates sector rotation thesis. Watch German competitiveness indicators; if German stock underperformance persists, it could trigger broader concerns about eurozone composition. Also monitor Stellantis stock performance as precedent; if Stellantis rebounds, it could suggest VW has similar recovery trajectory.
Affected Tickers & Coins: VOW (Volkswagen), STLA (Stellantis), BMW (BMW), DAI (Mercedes-Benz), RACE (Ferrari), WKL (Wolters Kluwer), NOK (Nokia), ENGI (Engie), NVDA, STOXX (Euro Stoxx 50)
Source: Financial Times