Powered by LumidaWealth.com
Lumida News
  • Home
  • EarningsNEW
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Macro
    • Markets
    • Real Estate
  • Lifestyle
    • Family Office
    • Health and Longevity
  • Themes
    • Aging & Longevity
    • AI
    • CRE
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
  • About Us
No Result
View All Result
Lumida News
No Result
View All Result
  • Lumida Wealth
  • Lumida Ledger
  • LUMIDA ETF
  • About Us
Home Themes AI

Tencent Mulls $5B Offshore Bond as AI Capex Accelerates — Global AI Debt $575B YTD Masks Credit Stress as SoftBank Pays Record Yields, Signaling Debt Market Bifurcation from Equity Rejection

by Team Lumida
October 8, 2026
in AI
Reading Time: 7 mins read
A A
0
Tencent Mulls $5B Offshore Bond as AI Capex Accelerates — Global AI Debt $575B YTD Masks Credit Stress as SoftBank Pays Record Yields, Signaling Debt Market Bifurcation from Equity Rejection
Share on TelegramShare on TwitterShare on FacebookShare on LinkedinShare on Whatsapp
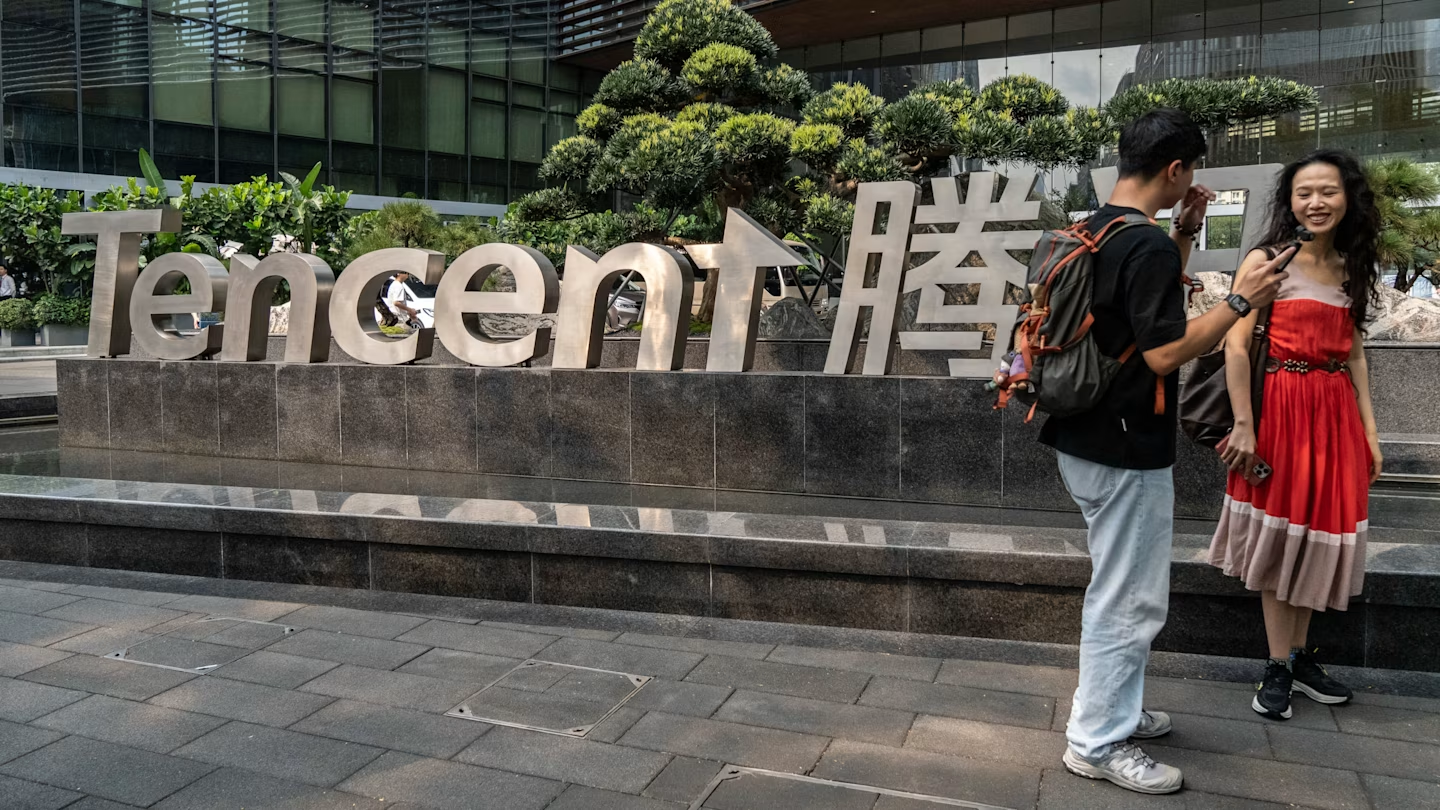
  • Tencent Holdings weighing $5 billion offshore bond offering (dollar and offshore yuan denominated), potentially this month (October 2026), marking second major capital raise in 4 months for AI capex acceleration. Prior June 2026 offering $4.7B (largest debt sale since 2020) for AI product/service development and debt refinancing. Tencent capex on AI and computing surged +176% in June quarter to 52.8 billion yuan ($7.9 billion), validating competitive intensity catching up to ByteDance, Alibaba, DeepSeek, Moonshot. Company developing in-house models (Hy4 targeting late 2026) to compete with top-tier agents. Two raises in 4 months ($4.7B June + $5B Oct consideration) suggests accelerated AI capex timeline beyond original budget or competitive pressure forcing incremental spending. Outstanding offshore notes ~$22B; no public bonds maturing 2026; one $USD bond due 2028. Raises timed amid rising yields (US 10Y at 5.3%+) and Firmus IPO collapse Friday same day (Oct 8), signaling debt investors still willing to finance AI despite equity market skepticism emerging.
  • Global AI-related debt issuance $575B+ YTD 2026 validates wave of tech debt financing but masks emerging credit stress signals. Goldman Sachs credit strategists report AI debt financing accelerating despite warnings about potential ROI failures if technology disappoints. SoftBank Group’s $11.1B junk-bond offering in September (one of largest corporate junk issuances on record) seen as litmus test for how debt investors valuate AI risk—and SoftBank paid record yields to clear deal. Interpretation: debt capital still available for AI but at materially higher cost, signaling credit markets pricing in elevated risk even as issuance volume remains robust. Tencent likely paying higher spreads than June 2026 raise due to widening credit conditions. Pattern: equity markets increasingly selective (Firmus IPO failed same day Tencent bond announced), but debt markets financing AI at premium pricing. Bifurcation validates Hayes thesis inflection: capex commitments need financing even as returns questioned.
  • Tencent capex acceleration (+176% AI spending) validates competitive consolidation in China AI model layer. Tencent capex $7.9B June quarter (52.8B yuan) represents catch-up to ByteDance (largest AI/compute spender in China) and hedge against Alibaba, DeepSeek dominance. Developing Hy4 model akin to best from DeepSeek/Moonshot signals Tencent recognizes late-to-market positioning in generative models. Also operates one of country’s largest AWS-like cloud services, creating vertically-integrated AI/cloud play. Two bond raises in 4 months (total $9.7B) locks in capex runway through 2027. Cost structure risk: if AI model commoditization accelerates (pricing compression between DeepSeek, Moonshot, Hy4, ByteDance models), Tencent’s $7.9B capex burn rate faces margin pressure despite competitive necessity. Capex acceleration by necessity (not optionality) validates Hayes overbuilding pattern: competitive dynamics force capex commitments regardless of return visibility.
  • Debt market bifurcation from equity validates staged capital structure exhaustion timing. Firmus IPO collapsed Oct 8 (equity reject), Tencent $5B bond consideration Oct 8 (debt accept at premium). Pattern: equity capital (public markets, venture) increasingly selective; debt capital (bonds, leverage) still available but costly. Tencent raising $9.7B in 4 months at escalating spreads validates debt market stress despite issuance volume. SoftBank record yields for $11.1B suggests credit spreads on AI-related debt widening 150bp+ above comparable credits. Consequence: tech companies funding AI capex increasingly via debt (higher leverage) rather than equity (dilution vs debt) or operating cash flow. This validates Hayes inflection timing: capex commitments lock in via debt (cheaper financing cost 2025-mid 2026), but debt cost rising sharply (yields/spreads up 300bp+) by late 2026. Forward risk: if AI returns disappoint 2027-2028, highly-leveraged tech companies (Tencent, SoftBank, others) face refinancing stress simultaneously as capex ROI deteriorates. Debt market bifurcation masks underlying leverage cycle compression.

What Happened?

Tencent Holdings Ltd. is considering an offshore bond sale of as much as $5 billion denominated in US dollars and offshore Chinese yuan, according to people familiar with the matter, potentially coming as early as October 2026. The contemplated offering marks the second major capital raise by Tencent in four months, following a $4.7 billion bond sale in June 2026—the company’s largest debt offering since 2020. The June proceeds were directed toward debt refinancing and developing artificial intelligence products and services. Tencent’s capital intensity for AI has intensified dramatically, with capital expenditures on AI and computing surging 176 percent to 52.8 billion yuan ($7.9 billion) in the June quarter, as the company seeks to develop in-house artificial intelligence models such as Hy4, targeted for launch in late 2026, to compete with rivals including ByteDance, Alibaba, DeepSeek, and Moonshot. The company operates one of China’s largest cloud computing services, positioning it as a vertically-integrated player across model development, cloud infrastructure, and computing provision. Global artificial intelligence-related debt issuance has exceeded $575 billion in 2026 according to Goldman Sachs credit strategists, despite mounting concerns about whether the technology will deliver sufficient returns to justify the scale of investments being made. SoftBank Group Corporation raised $11.1 billion through one of the largest corporate junk-bond offerings on record in September 2026, paying record yields to complete the sale.

Why It Matters?

Tencent’s contemplated $5 billion bond sale, combined with its prior $4.7 billion raise in June, signals that Chinese technology companies are accelerating artificial intelligence capital expenditures faster than originally budgeted, driven by competitive pressure to keep pace with ByteDance, Alibaba, and emerging rivals such as DeepSeek and Moonshot. The two raises within four months totaling $9.7 billion represent a significant acceleration in capital deployment, suggesting Tencent views the competitive window for AI model development as narrowing and requires immediate capex increases to remain viable in the model layer. However, the bifurcated reception of Tencent’s potential bond offering on the same day that Firmus Grid’s Australian data center IPO collapsed illustrates an emerging structural division in capital markets: equity investors are rejecting AI infrastructure valuations as too aggressive (Firmus failed), but debt investors remain willing to finance AI capex at materially higher cost. SoftBank’s September junk-bond offering at record yields signals that credit spreads on AI-related debt are widening significantly, indicating debt markets are pricing elevated refinancing and return-realization risk. Tencent’s 176 percent year-over-year increase in AI capex ($7.9 billion in the June quarter alone) validates the competitive dynamics driving capex acceleration, but also highlights leverage risk: companies are funding accelerating capex via debt at escalating cost, compressing margins and increasing refinancing risk if AI returns disappoint in 2027-2028.

What’s Next?

Monitor Tencent bond issuance pricing and spreads closely: if spreads remain under 200bps above comparable credits (validates debt appetite), suggests credit markets still confident in AI capex returns; if spreads exceed 250bps (validates credit stress), signals debt market repricing AI risk upward. Watch Tencent’s Hy4 model performance metrics when launched in late 2026: if achieves comparable performance to DeepSeek/Moonshot benchmarks (validates competitive catch-up), supports capex spending justification; if performance lags (validates competitive maturity), suggests capex inefficiency ahead. Track Tencent leverage metrics: if debt-to-EBITDA rises above 1.5x (validates leverage cycle), positions company for refinancing risk if capex ROI disappoints. Monitor competing AI model launches: if ByteDance, Alibaba, DeepSeek, Moonshot pricing compress models aggressively (validates commoditization), margin pressure on Tencent’s capex burn rate. Most critically, watch SoftBank’s junk-bond spread trajectory: if widen beyond 300bps (validates AI credit stress), signals broader tech debt market repricing underway. Finally, track Tencent management guidance on capex trajectory: if conservative or reduced in Q4 2026 earnings (validates peak capex inflection), validates Hayes thesis; if aggressive or increased, validates capex acceleration continuing into 2027. The two raises in four months position Tencent with runway through 2027, but rising debt cost creates margin compression risk if AI model returns plateau.

Affected Tickers and Coins: TCEHY | SFTBY | BABA

Source: Bloomberg

Previous Post

Firmus Grid IPO Collapses as Investors Balk at $30.4B Valuation — Nvidia-Backed Data Center Listing Fails to Find Support, Validating Hayes AI Capex Skepticism Inflection

Next Post

TSMC Q3 Revenue Jumps 51% as AI Demand Holds — Supply-Side Validation Masks Emerging Margin Compression as 3-6% Wafer Price Hikes Signal Peak Pricing Power Before 2027 Inflection

Recommended For You

Anthropic’s Public Benefit Structure Poses Unusual Risks for IPO Buyers: Seven Co-Founders Hold 50.1% of the Vote at a Targeted $1.5 Trillion-Plus Valuation

by Team Lumida
1 hour ago

Anthropic’s PBC structure, founder voting control and trust-elected board could limit shareholder influence in its $1.5 trillion-plus IPO, experts say.

Read more

CoreWeave and Nebius Slide About 5% After Hours as Microsoft and Alphabet Both Spend Less Than Expected on Capex, With Neoclouds Already Down 40% to 62% From Their Highs

by Team Lumida
1 hour ago

Neocloud stocks fell after hours as Microsoft and Alphabet both reported lower-than-expected capex, reviving worries about data center delays and debt costs.

Read more

Microsoft Hits Record Territory After Hours as Azure Grows 48% and Capex Comes In $6 Billion Below Forecasts, With Guidance Topping the Street

by Team Lumida
1 hour ago

Microsoft beat on revenue, EPS and Azure growth, spent less than expected on capex and guided above consensus, lifting shares about 3% after hours.

Read more

Microsoft Is Up 36% Since Its Last Report While Alphabet Is Down 5%, as Free Cash Flow Becomes the Scorecard for Tonight’s AI Earnings

by Team Lumida
17 hours ago

Microsoft and Alphabet report after the bell with investors rewarding AI spenders that still generate cash and options pricing a bigger Alphabet move.

Read more

OpenAI Plans to Buy Google’s TPU Chips to Speed Its AI Build-Out, as Oracle Opens Its Cloud to TPUs and Alphabet Reports Earnings Today

by Team Lumida
1 day ago
OpenAI Eyes $1.2 Trillion Valuation in Private Funding Round Before 2027+ IPO, Capitalizing on GPT-5.6 Success

OpenAI intends to buy AI chips from Google, Bloomberg reports, as Google’s TPUs gain ground as an alternative to Nvidia’s GPUs.

Read more

Cramer Says the Two-Day AI Rally Is No ‘All Clear,’ Pointing to CoreWeave Bonds Yielding Up to 15% as Data Center ETFs Sit 15% to 22% Below Their Highs

by Team Lumida
1 day ago
How CoreWeave’s Nvidia Partnership is Disrupting Cloud Computing Giants

Jim Cramer warned the AI rally doesn’t fix the data center trade’s funding problem, flagging neocloud debt, borrowed money and rising rates.

Read more

JPMorgan, Citi, BofA, Wells Fargo and Morgan Stanley Are Blocking Outside AI Agents After One Moved $100,000 Following a Password Reset

by Team Lumida
2 days ago

Five of the largest US banks are blocking external AI agents from customer accounts, citing fraud risk and unclear liability for agent-led transactions.

Read more

Nvidia Commits $3 Billion to Meta’s Stock Sale and Deepens Their AI Agent Partnership, as Meta Upsizes the First Wave of Its $95 Billion Raise

by Team Lumida
2 days ago
The AI Capex Machine Keeps Roaring — Nvidia’s Manufacturing Partner Hon Hai Crushes Estimates as Server Demand Drowns Out Recession Fears

Nvidia will invest $3 billion in Meta’s equity raise and expand their partnership on AI agents, as Meta lifts its first offering to about $37.5 billion.

Read more

Anthropic’s IPO Is Now a Bellwether for the Whole AI Trade, With 48% of Sales Flowing Through Three Cloud Giants and $417 Billion in Compute Commitments

by Team Lumida
2 days ago
Anthropic Tells Investors It Will Post a Second Straight Profitable Quarter Ahead of Nasdaq IPO

Anthropic’s IPO is a test for Big Tech and the AI trade, as 48% of its sales run through three clouds and growth slowed to 45% in the...

Read more

An Ex-Citadel Quant’s Hyperbolic Is Building Toward Physically Settled GPU Futures as CoreWeave’s Slide Sends Wall Street Looking for an AI Hedge

by Team Lumida
3 days ago

Hyperbolic, led by ex-Citadel quant Jasper Zhang, is building a GPU spot market aimed at physically settled futures as the CFTC reviews a CME cash-settled GPU contract.

Read more
Next Post
TSMC Q3 Revenue Jumps 51% as AI Demand Holds — Supply-Side Validation Masks Emerging Margin Compression as 3-6% Wafer Price Hikes Signal Peak Pricing Power Before 2027 Inflection

TSMC Q3 Revenue Jumps 51% as AI Demand Holds — Supply-Side Validation Masks Emerging Margin Compression as 3-6% Wafer Price Hikes Signal Peak Pricing Power Before 2027 Inflection

Goldman Sachs Urges Investors to Cut Risk: Is a Selloff Looming?

Goldman Sachs Warns AI Shift Leaves Middle Managers in Limbo — Organizational Restructuring Validates Scope of Automation Beyond Infrastructure, Signals Talent Concentration Risk and Wage Pressure as Pyramid Career Structures Collapse

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Related News

a white square with a blue logo on it

Meta Challenges EU’s Digital Markets Act Over Messenger and Marketplace Classification

June 3, 2025
Broadcom Amassing $60 Billion AI Chip Financing for Anthropic; $42B Class A Senior-Secured Banks; $18B Class B Junior Debt Blackstone $9B; Syndication Letters Sent; Nvidia $500B Partnership August; Hundreds of Billions AI Infrastructure Debt; Anthropic-Blackstone Fund Performance Boost; Data-Center Backlash Monitoring

Broadcom’s CEO Had to Step In to Save the $63 Billion Anthropic Chip Debt Deal, Agreeing to Higher Rates as Banks Balked at AI Risk

October 27, 2026
red and blue light streaks

Retail Money Heads for the Exits in Private Credit, Stress-Testing “Semi-Liquid” Funds

January 22, 2026

Subscribe to Lumida Ledger

Browse by Category

  • Lifestyle
    • Family Office
    • Health and Longevity
    • Legacy
    • Next Gen Wealth
    • Trust, Tax, and Estate
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Latest
    • Macro
    • Markets
    • Real Estate
  • Opinions
    • Investing Philosophy
    • Op-Ed
  • Research
    • Trackers
  • Themes
    • Aging & Longevity
    • AI
    • Biotech
    • CRE
    • Cybersecurity
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
    • Software
Facebook Twitter Instagram Youtube TikTok LinkedIn
Lumida News

Premium insights to help you invest beyond the ordinary. Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser

CATEGORIES

  • Aging & Longevity
  • AI
  • Alt Assets
  • Biotech
  • CRE
  • Crypto
  • Cybersecurity
  • Digital Assets
  • Equities
  • Family Office
  • Health and Longevity
  • Investing Philosophy
  • Latest
  • Legacy
  • Legacy Brands
  • Lifestyle
  • Macro
  • Markets
  • News
  • Next Gen Wealth
  • Nuclear Renaissance
  • Op-Ed
  • Private Credit
  • Real Estate
  • Software
  • Themes
  • Trackers
  • Trust, Tax, and Estate

BROWSE BY TAG

AI AI chips Amazon Apple Artificial Intelligence Banking Bank of America China Commercial Real Estate CPI data centers Donald Trump EARNINGS ELON MUSK Federal Reserve financial services generative AI Goldman Sachs Google India Inflation Interest Rates Investment Strategy Japan Jerome Powell JPMorgan Markets Meta Microsoft Nasdaq Novo Nordisk Nuclear Energy Nvidia oil OpenAI private equity S&P 500 SEC Semiconductor stock market stock surge Tech Stocks tesla Trump Whale Watch

© 2025 Lumida Wealth Management LLC is an SEC registered investment adviser. Privacy Policy. Cookies Policy.
Disclaimer Important Information This site is for informational purposes only. Information presented on this site does not constitute as investment advice.

Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser. SEC registration does not constitute an endorsement of the firm by the Commission nor does it indicate that the adviser has attained a particular level of skill or ability.

Lumida's website (referred to herein as the "Website") is limited to the dissemination of general information pertaining to its advisory services, together with access to additional investment-related information, publications, and links. Accordingly, the publication of the Website on the Internet should not be construed by any client and/or prospective client Lumida’s solicitation to effect, or attempt to effect transactions in securities, or the rendering of personalized investment advice for compensation, over the Internet.

Any subsequent, direct communication by Lumida with a prospective client will be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides.

‍Lead Capture Forms: By submitting your contact information in the forms on this site, you are not obligated to invest in Lumida's product or services.
‍Address: Lumida Wealth Management, 25 W 39th Street Suite 700, New York, NY 10018

No Result
View All Result
  • Home
  • Earnings
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Macro
    • Markets
    • Real Estate
  • Lifestyle
    • Family Office
    • Health and Longevity
  • Themes
    • Aging & Longevity
    • AI
    • CRE
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
  • About Us

© 2025 Lumida Wealth Management LLC is an SEC registered investment adviser. Privacy Policy. Cookies Policy.
Disclaimer Important Information This site is for informational purposes only. Information presented on this site does not constitute as investment advice.

Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser. SEC registration does not constitute an endorsement of the firm by the Commission nor does it indicate that the adviser has attained a particular level of skill or ability.

Lumida's website (referred to herein as the "Website") is limited to the dissemination of general information pertaining to its advisory services, together with access to additional investment-related information, publications, and links. Accordingly, the publication of the Website on the Internet should not be construed by any client and/or prospective client Lumida’s solicitation to effect, or attempt to effect transactions in securities, or the rendering of personalized investment advice for compensation, over the Internet.

Any subsequent, direct communication by Lumida with a prospective client will be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides.

‍Lead Capture Forms: By submitting your contact information in the forms on this site, you are not obligated to invest in Lumida's product or services.
‍Address: Lumida Wealth Management, 25 W 39th Street Suite 700, New York, NY 10018