- More than 90% of fed funds futures price no change at Wednesday’s meeting, according to CME FedWatch, even though nearly 84% of the market expects at least one quarter-point hike before year-end. Some analysts think the midterm elections next week make a surprise hike less likely because of the optics, American Banker reported.
- History offers little guidance. Since 1954, the FOMC has met in October or early November before a midterm 11 times, producing three hikes, four cuts and four holds, and it has approved just one pre-election hike since 1980: the 75 basis point move before the 2022 midterms.
- The inflation backdrop makes a hold harder to explain. September CPI rose 3.7% year over year, PPI climbed 6.3%, the steepest since 2022, and Thursday’s PCE report is expected to show headline inflation rising to 3.7% from 3.4% with core at 3.1%, according to CNBC.
- JPMorgan’s Michael Feroli said Warsh “will have to explain why the committee hiked after a two-tenths core PCE print” but is holding after an expected three-tenths reading, warning that an unexplained hold “less than a week before the midterm elections” would encourage thoughts that politics is driving policy.
What Happened?
The FOMC announces its decision Wednesday afternoon, followed by Warsh’s press conference. Allianz Trade’s Dan North expects the Fed to do nothing because a hike “would raise questions about political favor,” while Mutual of America’s Jerry Tempelman said the data show “no good reason for the Fed to delay tightening.” BNY’s John Velis argued for a hold on fundamentals, saying high oil prices from the Iran war are driving up costs that higher borrowing costs would not defray, while the AI buildout is raising chip and input costs that a hike could curb only by harming other parts of the economy. Goldman Sachs expects the Fed has settled on an every-other-meeting approach to hiking.
Why It Matters?
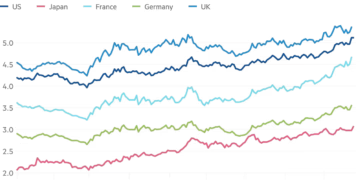
Under Warsh, who avoids forward guidance, the meeting carries more uncertainty than usual. Bank of America’s Aditya Bhave noted that under Powell or Yellen there would be “basically zero chance” of a hawkish surprise six days before the midterms, and the fact that markets still see some risk shows how much has changed. A hold with little explanation could feed doubts about Fed independence, while a hawkish message could push short-term yields higher; the 10-year yield was around 5.03% and the two-year 4.774% ahead of the decision.
What’s Next?
Investors will parse the statement and press conference for clues on December, then turn to Thursday’s PCE report. TD Securities warned that one bad inflation report or strong labor data could lead markets to price larger odds of a 50 basis point hike. Since Warsh took over in May, stocks have generally fallen on Fed meeting days and gained the day after, with the S&P 500 rallying at least 1% on each of the three post-meeting days, according to DataTrek Research.
Affected Tickers and Coins: SPY, TLT, SHY
Source: American Banker, CNBC