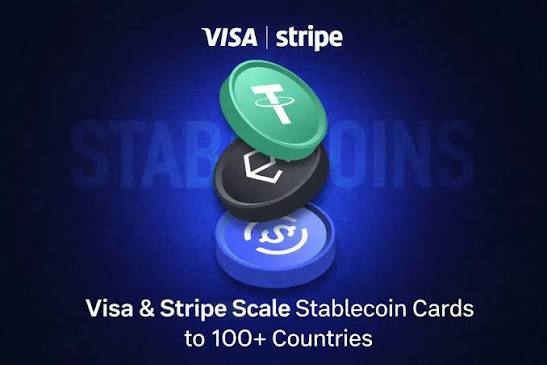
- Stripe expects its stablecoin card programmes to reach more than 100 countries by year-end, with current customers including Kraken, Ramp and payments app Morse. Henri Stern, co-founder of wallet infrastructure firm Privy which Stripe acquired last year, has taken on an additional role overseeing stablecoins and crypto across the company.
- Stablecoin card spending reached about $1.2 billion last month according to Paymentscan, triple the figure a year earlier, within a digital dollar market exceeding $300 billion. That annualises to roughly $14 billion, a negligible share of a global card payments market measured in tens of trillions.
- Stripe is combining the new business with existing infrastructure, having issued more than 400 million cards and processed hundreds of billions of dollars in card volume since 2018, alongside Bridge, the stablecoin infrastructure company it bought for $1.1 billion in 2024.
- The company has assembled a broad stack. Beyond Bridge and Privy it has partnered with Paradigm to develop Tempo, a blockchain designed for payments, and is a founding investor in Open Standard, which is building Open USD, a stablecoin aiming to challenge Circle USDC and Tether USDT. Bridge co-founder Zach Abrams recently moved to run Open Standard full time.
What Happened?
Stern said the approach is to plug stablecoins into infrastructure Stripe already operates rather than requiring customers to adopt a separate crypto stack. For a company such as Ramp that could mean extending a corporate card into new countries using stablecoins instead of rebuilding banking connections market by market, while Kraken has explored letting customers spend from accounts holding digital assets. Stern said Stripe intends to remain completely stablecoin and blockchain agnostic, and that its products should work well together without locking customers into its ecosystem. The company is also exploring tokenised deposits, decentralised finance uses and accepting more digital assets, though the bulk of the work remains in stablecoins.
Why It Matters?
The position Stripe occupies relative to Circle deserves more attention than the agnostic framing suggests. Many Stripe card programmes currently run on USDC, and Stripe is simultaneously a founding investor in the company building a stablecoin designed to compete with it, staffed by the co-founder of the infrastructure business Stripe itself acquired. Circle depends on distribution partners to reach users, and one of the largest of those partners is funding an alternative. For anyone holding Circle equity, that is a structural vulnerability which the neutral language obscures, and it is the kind of competitive dynamic that appears in results only after it has already happened. The scale figures need stating plainly so the growth is not overread. Tripling annual spending to $1.2 billion a month is impressive in percentage terms and immaterial in absolute terms against global card volumes. Stablecoin payments are at the stage where the trajectory matters more than the level, and the honest reading is that this is early rather than arrived. What makes Stripe interesting is the completeness of the stack rather than current volumes. It owns card issuing at scale, wallet infrastructure, stablecoin infrastructure, a payments blockchain and a stake in a stablecoin issuer, which is the most integrated private position in crypto payments. The approach also suggests the realistic adoption path is embedding stablecoins inside existing fiat products rather than replacing them, which is a less dramatic outcome than the disintermediation narrative and a more probable one. Stripe is private, so there is no listed way to own this directly, and the read-through falls to Circle, Tether and the card networks whose rails these programmes use.
What Next?
Watch whether Open USD actually launches and whether Stripe card programmes migrate to it from USDC, since that would convert a potential conflict into a realised one for Circle. Monthly stablecoin card spending is the measurable series, and whether it continues tripling or decelerates will indicate if this is genuine adoption or early enthusiasm. The 100-country target by year-end is a dated commitment worth checking against. Regulatory developments matter here too, with the European Central Bank pushing to restrict stablecoin yields and ESMA making tokenisation a supervisory priority from 2027, both of which affect how these products can operate in Europe. Tokenised deposits are the other area Stern flagged, and any concrete move there would be significant given bank interest in the same territory.
Affected Tickers and Coins: CRCL, USDC, USDT, V, MA
Source: CoinDesk