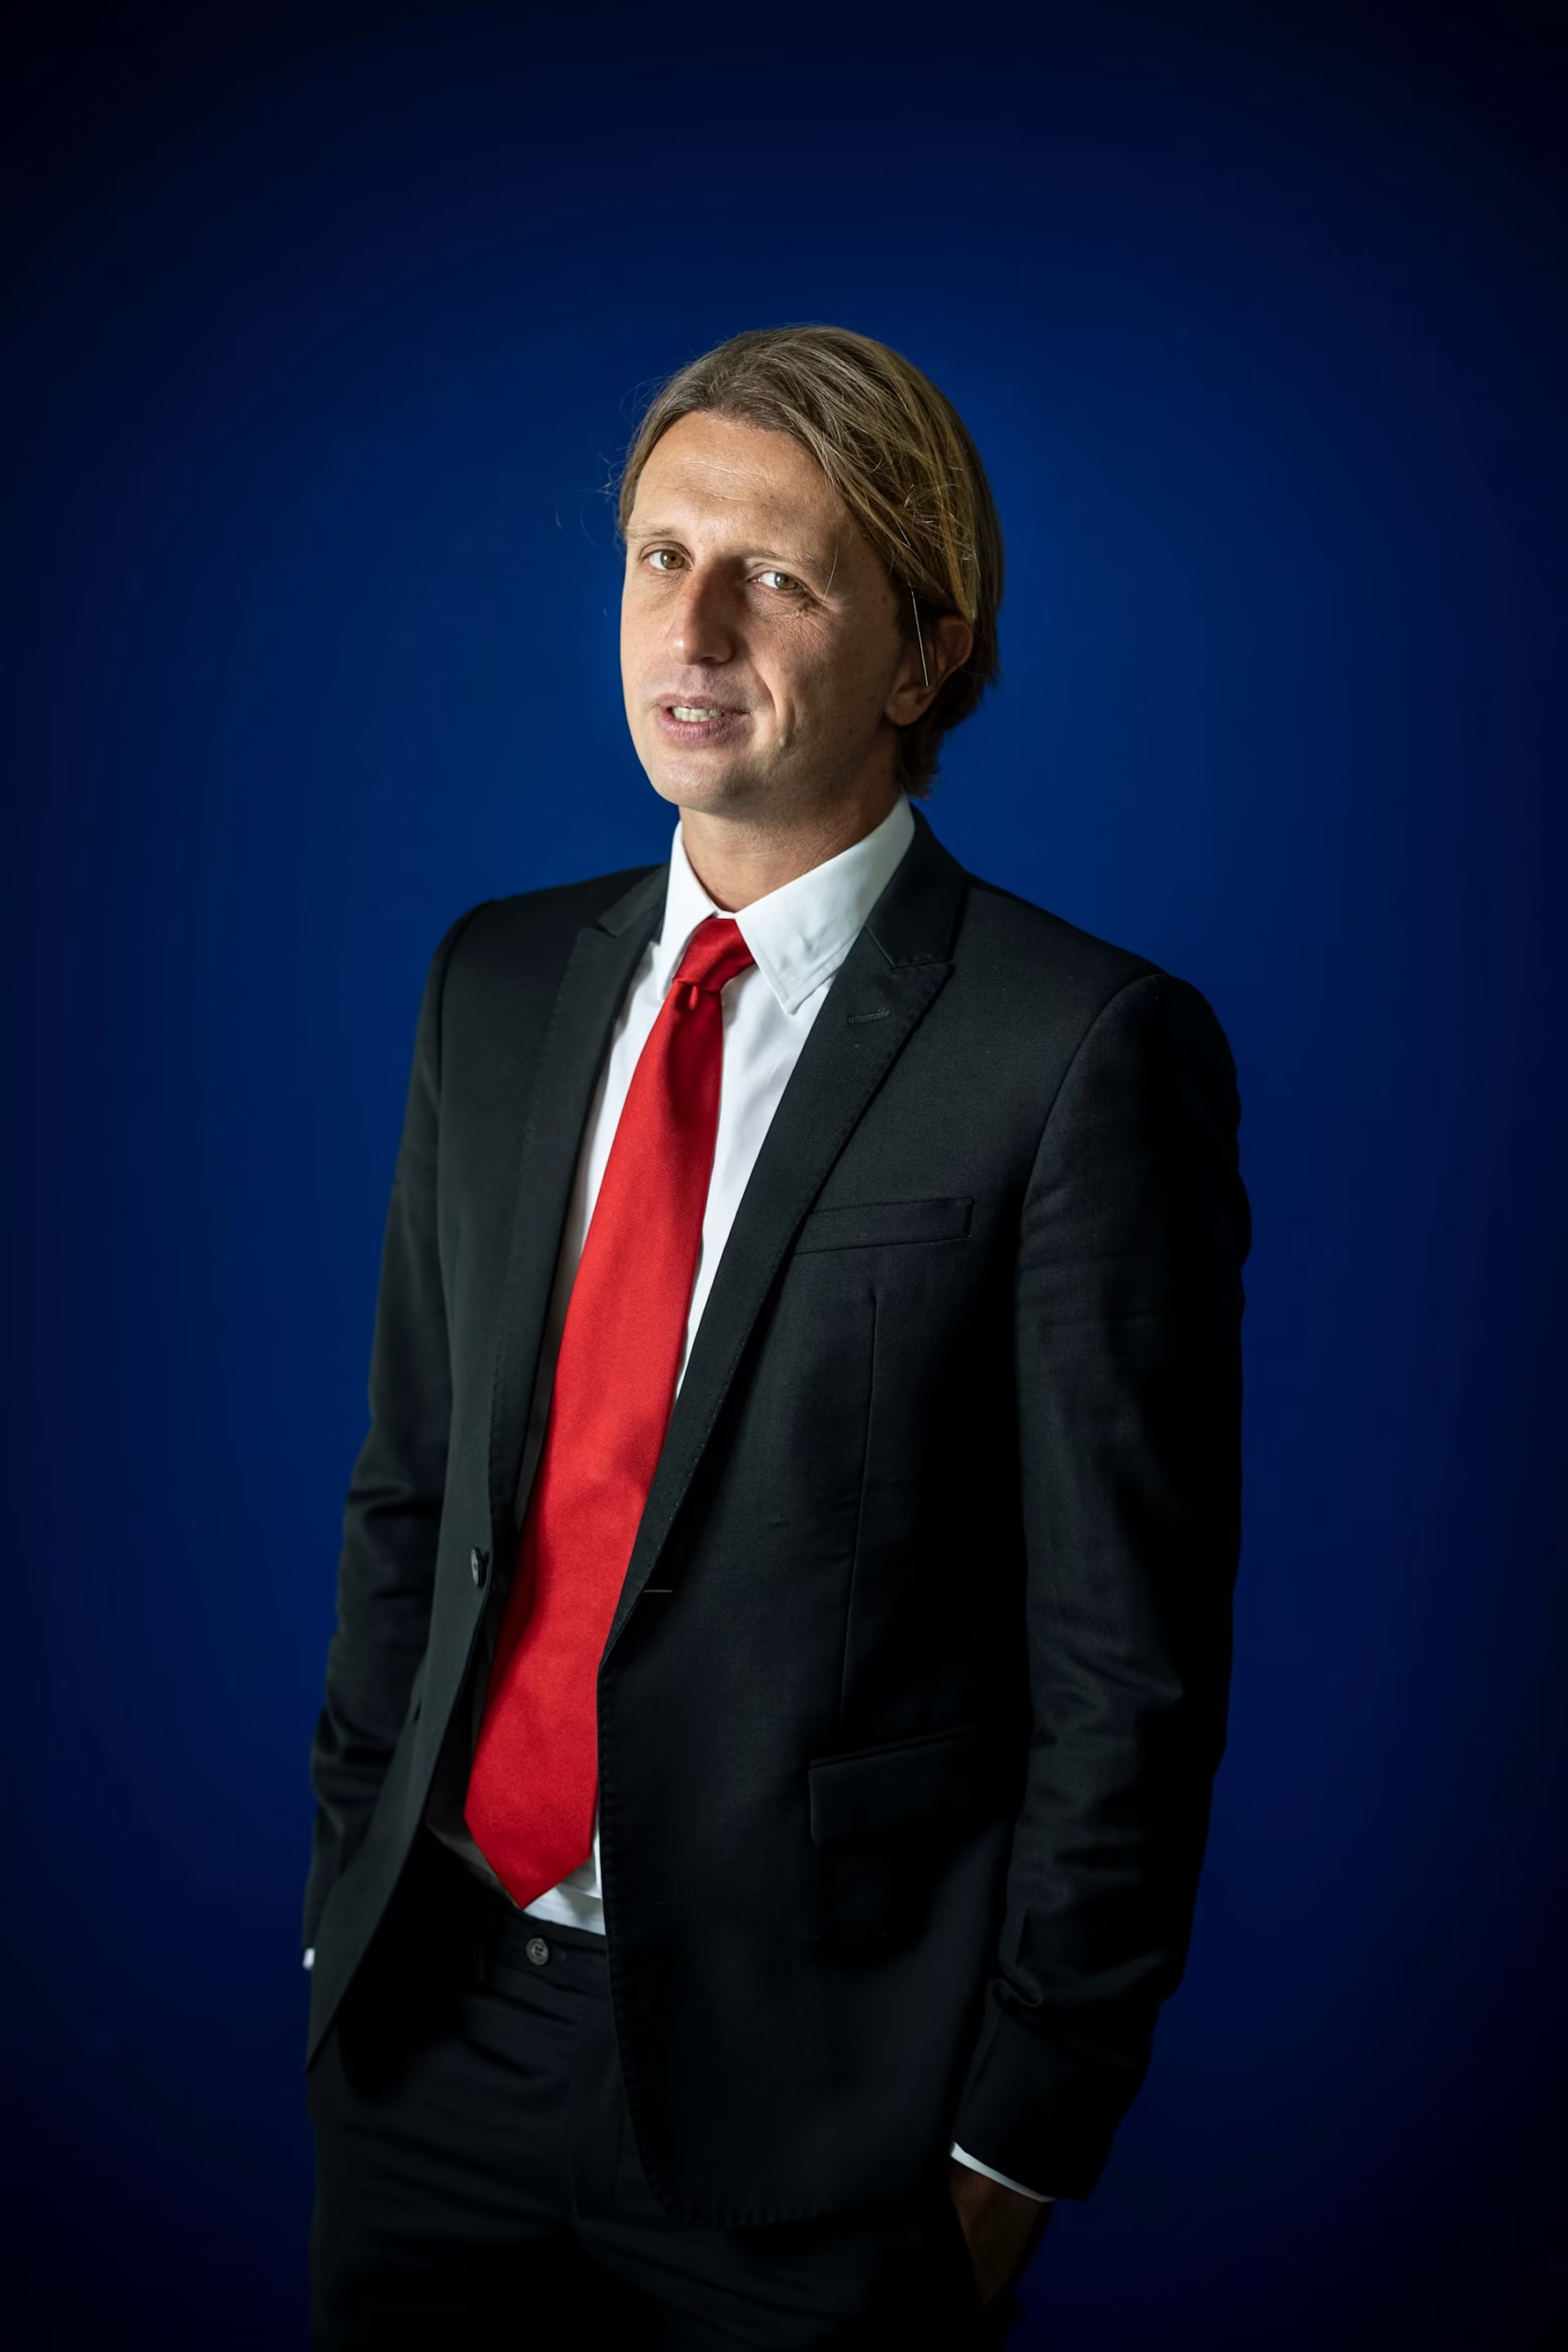
- Revolut CEO Nik Storonsky outlined vision for “world’s first truly global bank” with “effectively zero risk” business model in FT interview. Revolut now valued at $115 billion with 80 million customers across 40 countries after securing French banking license (September), UK authorization (March), and OCC approval (US). Storonsky, worth $33bn himself, sports new sharp suit for meeting (vs usual beach bum look), signaling confidence in regulatory progress. Interview held in Revolut’s ambitious Paris HQ (work in progress). IPO rumors suggest valuation could reach $200bn within two years with potential dual listing in New York and London.
- Storonsky’s risk management philosophy shaped by experiences at Lehman Brothers (collapse post-2008) and Credit Suisse (now defunct): avoid complex risks. Revolut’s loan-to-deposit ratio of 6% is extraordinarily low vs 100% industry average; CEO pledges to never exceed 10-20%. All loans sold off balance sheet via securitizations. Return on equity claimed at 40-50% (once excess capital deducted)—double best-performing rivals. Model is “to have effectively zero risk for the business.” Organic technology development (no acquisitions) contrasts with legacy banks like Citigroup (antiquated systems from acquisition mergers).
- Geopolitical fragmentation (Russia-Ukraine, Middle East, US-China tensions) hampers global expansion mission despite strong regulatory progress. Customer vetting challenging due to sanctions requirements. However, Revolut benefits from European talent advantages: 15,000 staff from 110 countries, high-quality talent “much cheaper compared to US, especially California.” Ireland penetration is 80% of population using Revolut (though not yet as primary bank). Competitive advantages: low fees, minimal friction, zero branches/call centers, aggressive product innovation vs traditional banks.
- Risk management credibility tested by recent cybersecurity incident: scam hours before FT interview saw bank hand over personal data of hundreds of wealthy clients to cybercriminals posing as Italian officials; $3mn ransom demanded. Prior issues: 2021-2023 audit dispute over revenue origin; 2024 fine for insufficient anti-money-laundering controls. Despite control shortcomings, Storonsky’s vision of European tech champion comparable to Jeff Bezos/Elon Musk has won policymaker confidence. QuantumLight venture funds ($850mn combined, $100mn personal capital) using AI-driven analysis; claims “top 5%” returns globally.
What Happened?
Revolut CEO Nik Storonsky gave FT interview outlining vision for global retail bank with “effectively zero risk” model. Revolut valued at $115B with 80M customers across 40 countries; recent banking licenses from France, UK, OCC (US) granted post-March. Storonsky worth $33B personally. Loan-to-deposit ratio 6% (vs 100% industry average); claimed ROE 40-50% (2x rivals). All loans sold off balance sheet via securitizations. Organic technology platform avoids acquisition legacy issues plaguing Citigroup. IPO rumors suggest $200B valuation within two years. Storonsky cites Lehman/Credit Suisse experiences as shaping low-risk philosophy. Geopolitical fragmentation (Russia-Ukraine, Middle East, US-China tensions) hampers 100+ country global bank goal. Cybersecurity incident disclosed hours before interview: cybercriminals obtained wealthy clients’ data, demanded $3mn ransom.
Why It Matters?
For traditional bank shareholders (Citigroup, others), Revolut represents existential competitive threat: low-cost, high-efficiency, technology-first retail banking model with 40-50% ROE vs legacy banks’ 15-20% ROE. For fintech investors (Block, PayPal), Revolut’s $115B valuation and expansion to 100+ countries validates that payments/fintech could disrupt banking. For emerging market investors, Revolut’s ability to operate across 40 countries despite geopolitical fragmentation validates cross-border fintech opportunity. For IPO investors, Revolut IPO at $200B (if materialized) would be among largest fintech IPOs ever—validating Storonsky’s European tech champion narrative vs California AI dominance. For venture capital, QuantumLight funds’ “top 5%” returns via AI-driven analysis could accelerate AI adoption in investment processes.
What’s Next?
Monitor Revolut’s IPO timeline; if company launches dual listing (NYC/London) at $150B+, it would validate Storonsky’s European success narrative. Watch for additional banking license approvals in key markets (Asia, Middle East); if Revolut expands to 50+ countries, it validates global bank thesis. Track Revolut’s lending exposure; if loan-to-deposit ratio creeps above 10%, it could signal philosophy drift away from low-risk model. Monitor cybersecurity/control improvements post-incident; if additional breaches surface, IPO valuation could face pressure. Watch traditional bank earnings for Revolut competitive impact; if deposits/market share losses accelerate, it validates disruption thesis. Track QuantumLight fund performance; if returns sustain “top 5%”, it could drive venture capital capital flows toward AI-first investing. Also monitor Storonsky’s tax residency and wealth management decisions; if yacht/tax controversies escalate, it could create regulatory/political pressure on Revolut growth trajectory.
Affected Tickers & Coins: SQ (Block), PYPL (PayPal), LPLA (LPL Financial), C (Citigroup)
Source: Financial Times