- The Securities and Exchange Commission has a crypto custody proposal covering both investment firms and broker-dealers under review at the White House Office of Management and Budget. Once cleared, the agency can formally propose it and open a public comment period.
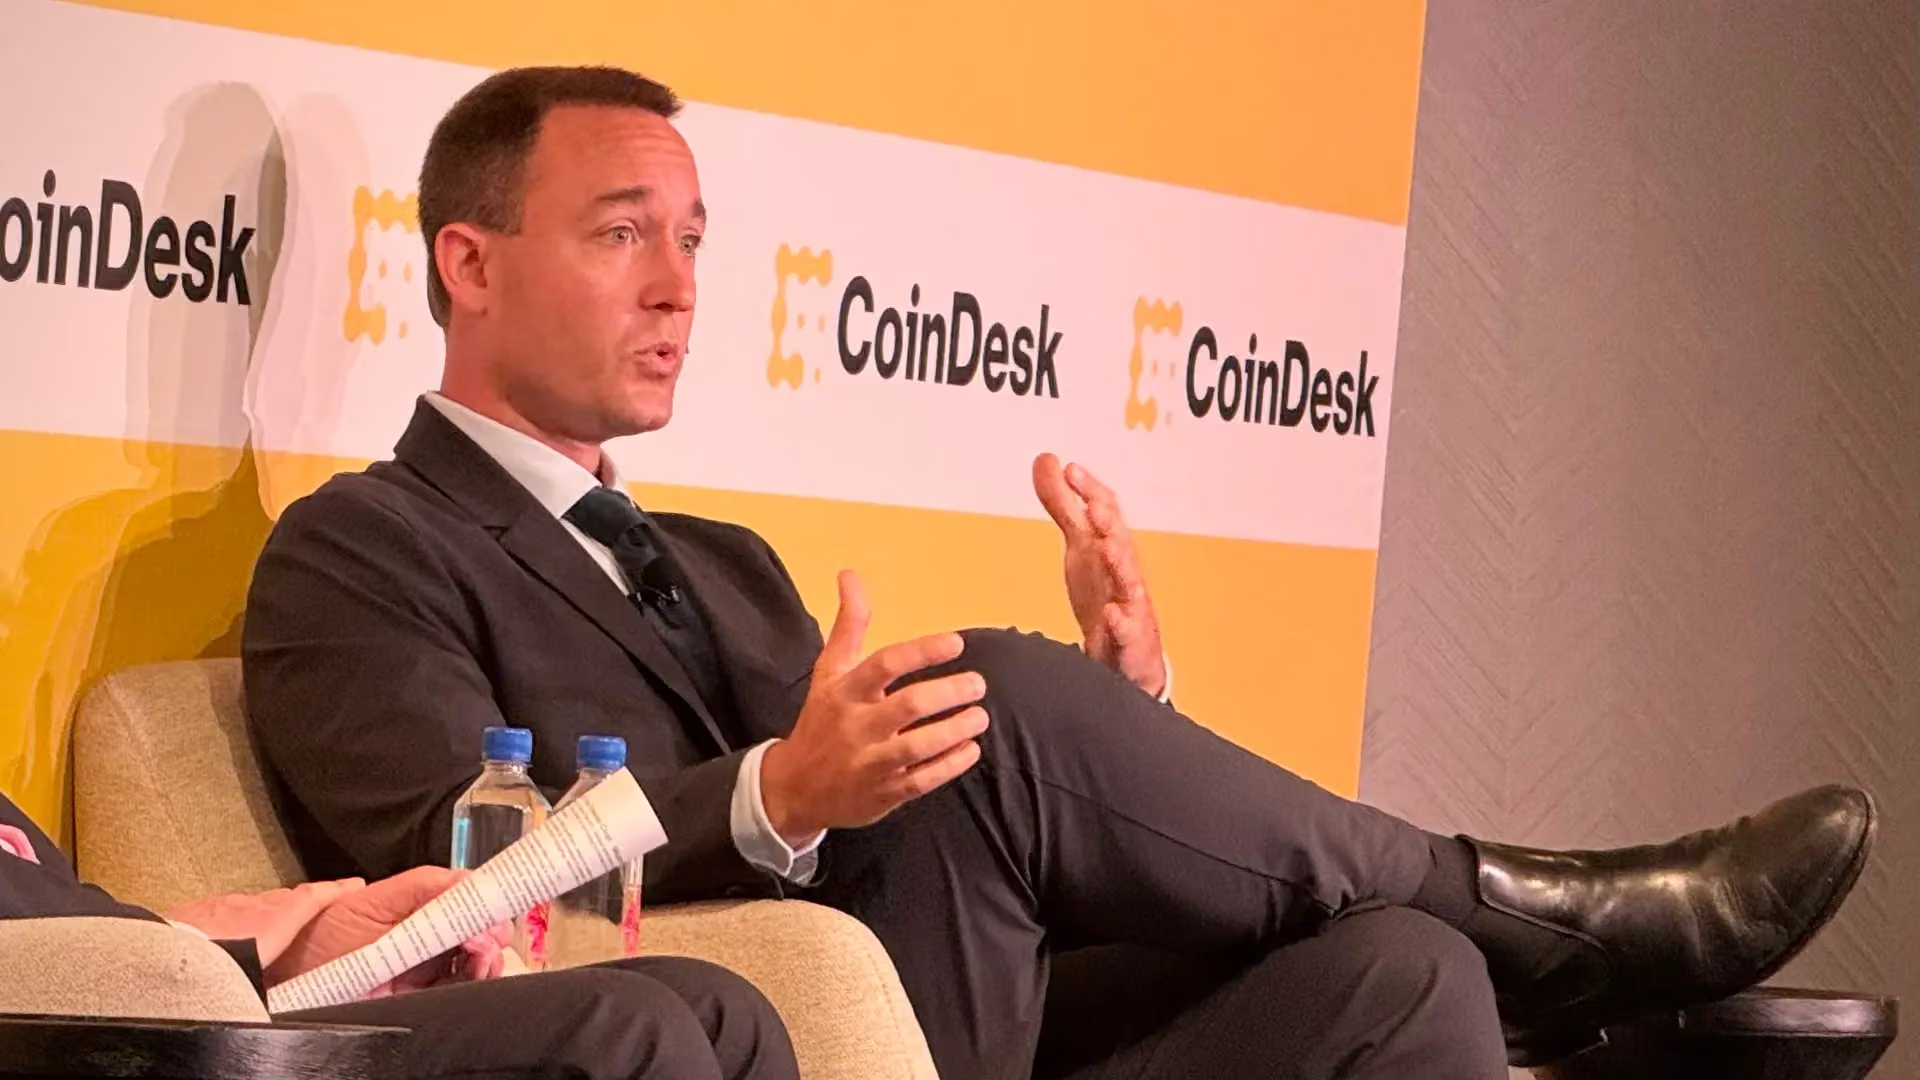
- Taylor Lindman, chief counsel of the SEC Crypto Task Force, said the rule is intended to let the market understand how a broker-dealer can hold a non-security crypto asset without needing special registration, and to clarify for investment advisers where client assets may be held, including at a state-chartered trust.
- Interim guidance is already in place. The SEC issued a staff statement in December steering broker-dealers on crypto custody until rules are finalised, and in September 2025 permitted investment advisers to use state-chartered trusts as qualified crypto custodians.
- The agency previously attempted a custody rule in 2023, when then-chair Gary Gensler said crypto firms themselves would not qualify to hold the assets. That rule never reached final form and was abandoned after President Trump appointed crypto-friendly leadership.
What Happened?
Speaking Tuesday at the CoinDesk Policy and Regulation event in Washington, Lindman described the work as foundation laying and acknowledged that some of it is boring. He said the aim is to bring existing securities intermediaries and market participants into a position where they are comfortable using blockchain and holding and transacting crypto assets, covering both those that are securities and those that are not. He framed it as taking what was once treated as a unique and frightening asset and placing it within a durable framework, meeting the market where it is. The custody effort sits alongside a proposed rule permitting crypto offerings and the recent exemption clearing the way for tokenized securities venues.
Why It Matters?
Custody is the rule that actually determines whether wealth managers can hold crypto for clients, and it receives a fraction of the attention that trading venue announcements attract. Registered investment advisers are bound by qualified custodian requirements, so an adviser cannot allocate to an asset it has no compliant way to hold, regardless of how many venues exist to trade it. Lindman description of letting broker-dealers hold non-security crypto without special registration is therefore the single most consequential item in the current SEC agenda for advisory firms, more so than the tokenized equity exemption that moved markets last week. The state-chartered trust route is the practical detail worth noting, since it creates a qualified custodian path that does not require a bank and is already available under the September 2025 letter. The durability problem applies here as much as elsewhere and is sharper because the history is documented. Gensler pursued a custody rule in 2023 on the premise that crypto firms could not qualify as custodians, that effort was scrapped on a change of administration, and the current proposal takes the opposite view. Custody policy has now flipped once with political control, which matters because advisers select custodians and build operational infrastructure on multi-year horizons. A rule that can reverse in three years is a weaker foundation than the finality of a statute would provide, and Congress has declined to supply one.
What Next?
OMB clearance is the immediate gate, after which the SEC can publish the proposal and open comment. The comment period is where custodians, advisers and crypto firms will contest the definition of a qualified custodian, and that definition is the part advisers should read closely. Watch whether the final rule preserves the state-chartered trust route established in September 2025, since removing it would narrow the options considerably. The December staff statement remains the operative guidance for broker-dealers until the rule is final, so its treatment in the proposal indicates how much continuity to expect. There is no published timeline for any of this, and rulemaking of this type typically runs many months from proposal to adoption. For advisory firms, the practical step now is to confirm which custodians their platform supports for crypto and under what legal basis, so the rule can be assessed against existing arrangements rather than in the abstract.
Source: CoinDesk