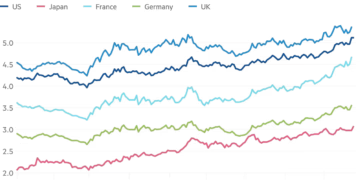
- The 30-year Treasury yield reached 5.446% Thursday morning, a level not seen since 2004. The 10-year jumped to 5.15%, last hit in 2006, and the five-year traded above 5%, also the highest since 2006. The Federal Reserve raised its target range last week by a quarter point to 3.75% to 4.0%.
- Auto loan pricing has barely moved. New-vehicle loan rates rose about 20 basis points over the past two months and used-car rates about 10 basis points, according to Cox Automotive chief economist Jeremy Robb in a September 21 report.
- Rates remain below year-ago levels. Experian data shows the average new car loan rate was 6.35% in the second quarter of 2026 against 6.79% a year earlier, with an average term of 5.8 years, while used car loans averaged about 11.2% against 11.57%, with terms near 5.7 years.
- Borrowers are already stretched at those levels. The average new car costs roughly $50,000 per Kelley Blue Book, the average amount financed was $43,610 with a monthly payment of $765, and used buyers financed $27,852 at $542 a month.
What Happened?
Yields have climbed across the curve as stronger-than-expected economic data fuelled inflation concerns and expectations of further Federal Reserve tightening. Patrick Manzi, chief economist at the National Automobile Dealers Association, said many auto loan rates move with the five-year or 10-year Treasury and that the recent run-up in yields should push auto loan rates higher. Robb noted the moves so far are unlikely to change average payments substantially but may weigh on consumer psychology and discourage large purchases. Lenders also weigh credit score, loan term and whether the vehicle is new or used, and captive finance arms sometimes offer below-market rates on slower-selling models in place of a larger upfront discount.
Why It Matters?
The gap between the bond market and the loan market is the real story. Treasury yields sit at 20-year highs while average auto loan rates are lower than they were a year ago, which means consumers are currently borrowing against a bond market that no longer exists. The 20 basis point increase over two months is the beginning of that adjustment, not the completion of it, and the repricing still to come is considerably larger than what has already occurred. Anyone modelling consumer credit on current average rates is working from stale inputs. The arithmetic understates the impact when expressed monthly. A one percentage point increase on a $43,000 loan over 72 months raises the payment by about $20, which sounds immaterial, but it adds roughly $1,483 to total interest, and a two point move adds nearly $3,000. Against an average new car price near $50,000 and payments already at $765, that is a meaningful erosion of affordability for households the Federal Reserve is explicitly trying to slow. For investors the useful read is as a credit indicator rather than a consumer tip. Auto lending is typically where household stress appears first, because the loans are large, the terms are long at 5.8 years, and the collateral depreciates. Combined with manufacturing output falling and durable goods down 0.5%, and with PepsiCo reporting that price cuts failed to lift volume, this is a third piece of corroborating evidence that the consumer is constrained. Used car rates above 11% are the segment to watch, since that is where subprime borrowers concentrate.
What Next?
Watch third quarter Experian data for whether average rates finally turn higher, as that would confirm the lag is closing and quantify how much repricing is arriving. Auto loan delinquency data is the more important series for anyone assessing consumer credit, particularly in the used segment at 11.2%. The October Federal Reserve meeting matters, though the five and 10-year yields driving auto pricing respond more to inflation expectations than to the policy rate itself. Track whether captive finance arms expand subsidised rate promotions, since a rise in those offers would indicate manufacturers are absorbing the rate increase to protect volume, which shifts the cost from consumers to automaker margins. Loan terms are the other tell: any extension beyond the current 5.8-year average would signal lenders stretching to keep payments affordable, which historically precedes deteriorating credit performance.
Affected Tickers and Coins: ZB, ZN, ZF, ALLY, KMX, AN
Source: CNBC