Dollar Rallies to Six-Month High; Bloomberg Spot Index +2% Two Weeks; Highest Level Since July
US dollar headed for best two-week stretch in six months. Bloomberg Dollar Spot Index gained ~2% past two weeks, climbing to highest level since July. Options pricing points to further gains. Reversal from narrative prevailing past two years (de-dollarization calls amid tariffs, $40T US debt surging). Confluence of events driving rally: Federal Reserve’s hawkish pivot (first hike in three years, signaling more to come), continued strength in AI capex boom, heightened geopolitical tensions reaffirming safe-haven appeal. Andreas Koenig (Amundi head of global FX): “US is still place with AI growth, leading capex spending, margins/earnings good. Rate differential positive, supportive for dollar.”
Treasury Yields at Multiyear Peaks; Rate Differentials vs Global Markets Fueling Dollar Inflows
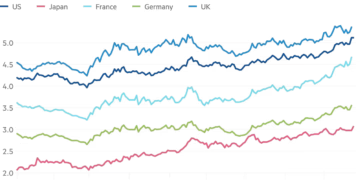
Strong US economic data (PMI report from Article 140) heralded more Fed rate increases. Treasury yields pushed to new multiyear peaks (10-year 5.225%, 30-year 5.502% from Article 143). Higher US rates attractive to global capital seeking yield, supporting dollar. Meanwhile technology-heavy Nasdaq 100 (Article 140) climbed to record. Oil prices resumed advance (validating commodity strength). Alex Cohen (Bank of America strategist): “We now see risk for dollar strength to continue into year end.” Validates consensus on sustained rally. Bloomberg data shows speculators had actually slashed bullish dollar positions heading into Fed pivot, creating “wrong-footed” reversal opportunity.
Euro Weakness (-3% YTD) vs Dollar; ECB Caught in Policy Trap; Citigroup Short Euro Recommendation
Euro lost >3% against greenback YTD. Daniel Tobon (Citigroup strategist) positioned short euro vs dollar since January (profitable trade). Estimates dollar index can rally another 1%. ECB caught in policy trap: raising rates risks negative growth knock-on effects (oil prices weighing on eurozone growth), forcing eventual policy reversal. Tobon: “ECB reaching point that starts having negative knock-on effects, might force them reverse policy down line,” leaving dollar better positioned vs euro. Validates eurozone growth stress (Article 135 VW fragility, Article 133 bond rout deepening globally).
Geopolitical Risk Reaffirming Dollar Safe-Haven Status; De-dollarization Trade Sidelined
Daragh Maher (HSBC senior FX strategist): “When world again seems falling apart…we’re running into dollar. Debasement story gets completely sidelined.” Validates that geopolitical tensions (Iran conflict, Taiwan Taiwan/trade uncertainty from Articles 136, 144) overriding long-term fiscal deficit concerns. Safe-haven narrative temporarily eclipsing “debasement trade” (shift into gold/assets). Relative-strength index for Bloomberg dollar gauge climbed above 70 (overbought territory), but haven appeal persisting. Seasonality helping (final full week September historically dollar’s strongest over past decade).
Fiscal Deficit Headwinds Remain; Long-Term Dollar Outlook Clouded Despite Near-Term Rally
Despite strong near-term momentum, long-term dollar outlook remains ambiguous. Massive government deficits, policy risk, interventionist Treasury dampening outlook. Maher: “Ambiguous relationship” between Treasury yields/dollar due to high US fiscal deficits. “We don’t think dollar will knock it out of park. It’s going to be modest dollar appreciation.” Nathan Thooft (Manulife Investment Management): Markets pricing ~90bp Fed hikes next 12 months (high bar). If upcoming inflation/labor/growth data show cooling, Fed may dial back hawkish messaging, limiting dollar upside. Validates Article 140 consumption deceleration risk thesis (Morgan Stanley 40bp real consumption decline forecast).
What Happened
Bloomberg Dollar Spot Index +2% past two weeks (highest since July). Fed hawkish pivot, strong US economic data, Nasdaq record, oil rally supporting dollar. Euro lost 3% YTD. Speculators had slashed bullish dollar positions before Fed surprise (creating reversal opportunity). Bank of America (Cohen), HSBC (Maher), Citigroup (Tobon) all bullish USD strength continuing to year-end. Tobon estimates dollar index rally another 1%. ECB trapped by high oil prices (growth risk if rates higher). Citigroup short euro/long dollar since January (profitable). Treasury Secretary Bessent’s bond buybacks + yen support moves interpreted negatively for dollar but failed to prevent rally. Relative-strength index overbought (>70) but geopolitical tensions reaffirming safe-haven flows.
Why It Matters
For currency traders, dollar strength validates safe-haven bid (geopolitical premium) overriding fiscal deficit concerns (short-term). For emerging market investors, stronger dollar headwind (EM debt servicing costs rise). For US exporters, dollar strength headwind (competitiveness). For global asset allocators, rate differential (US 5.2%+ vs lower global rates) attractive for USD positioning. For oil exporters (Russia, Iran, Saudi), dollar strength erodes purchasing power. For gold investors, debasement narrative sidelined (safe-haven dollar preferred over gold). For eurozone, weakness validates competitiveness boost (cheaper exports) but ECB policy trap validates growth pressure. For Fed, dollar strength validates credibility on hawkish pivot (capital inflows).
What’s Next
Monitor Fed speaker communications; if continue hawkish messaging, validates dollar rally persistence. Track ECB policy decisions; if reverse course (rate cuts), validates Citigroup thesis (euro weakness). Watch Treasury yields; if break above 5.3%, could accelerate dollar inflows. Monitor geopolitical tension levels; if ease (Iran resolution, Taiwan stability), could undermine safe-haven bid. Track US consumption data (Article 140 concern); if weaken significantly, could force Fed dovish shift (dollar headwind). Also monitor speculators’ dollar positioning; if they rebuild longs aggressively, could signal complacency. Finally, watch relative-strength index; if stays overbought >70 for extended period, validates stretched momentum (reversal risk).
Affected Tickers & Exchanges:
UUP (US Dollar Index ETF, NASDAQ) | EUR/USD (Currency Pair) | USO (Oil Fund, NYSE) | QQQ (Nasdaq-100, NASDAQ) | GLD (Gold ETF, NYSE) | BAC (Bank of America, NYSE) | HSBC (HSBC Holdings ADR, NYSE) | MFC (Manulife Financial, NYSE) | C (Citigroup, NYSE) | TLT (20+ Year Treasury, NASDAQ) | IEF (7-10 Year Treasury, NASDAQ)
Source: Bloomberg