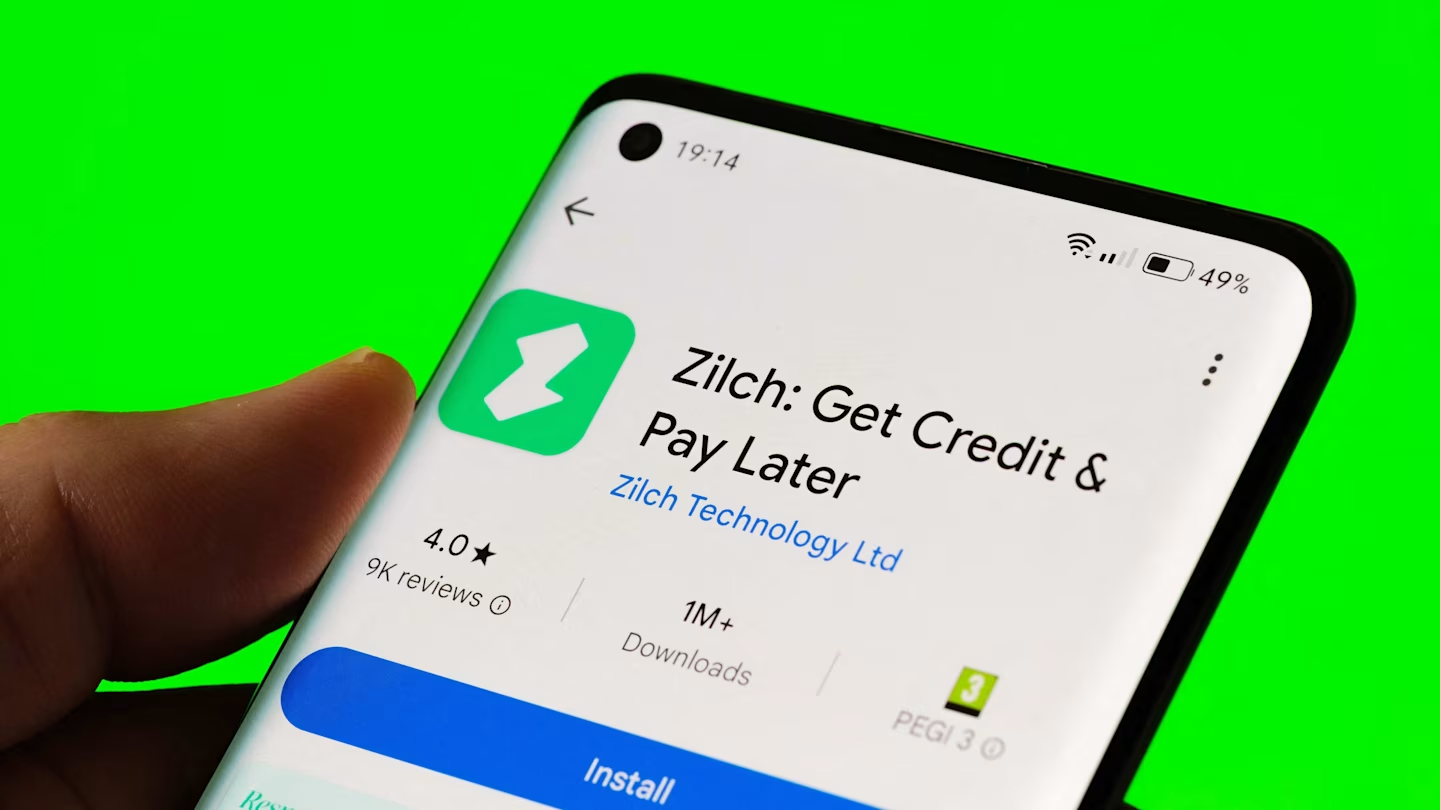
- Zilch launching IPO process next year, inviting investment banks to pitch for flotation roles on London Stock Exchange. Company valued $2B in 2021 during fintech boom, but maintained valuation in subsequent funding rounds—FY2025 performance (£10.5M loss, down from £50M prior year) unlikely to support peak valuation at IPO. Company targeting profitability by listing date, validating that path to IPO hinges on earnings inflection. Backers include eBay, Goldman Sachs, DMG Ventures (Daily Mail investment arm), Czech billionaire Karel Komárek’s KKCG ($175M led in November deal).
- Zilch business model validates fintech consolidation toward integrated financial services. Founded 2018; 6M customers; offers cashback debit card, buy-now-pay-later products, zero-interest loans. Revenue streams: targeted advertising based on transaction data (validates data monetization, validates Articles 169/174 on wealth concentration → luxury goods shift, now extending to retail credit). January acquisition of Lithuanian neobank Fjord Bank granted European banking license, enabling pan-European lending (validates Article 160 India EM expansion thesis applied to UK fintech: geographic arbitrage on regulatory/cost bases).
- Competitive landscape validates UK fintech IPO revival. Monzo (digital neobank) in discussions with Brazilian Nubank on takeover/stake sale. Starling (digital neobank) also considered IPO candidate. OakNorth (lender) backed by LSEG (London Stock Exchange owner). SumUp (UK card-reader company) reportedly planning Europe/UK listing (Article 160 precedent). All signaling fintech sector IPO recovery after multiyear drought. LSE battling takeovers of UK-listed companies, viewing fintech IPOs as growth opportunity.
- Zilch IPO timing validates consumer credit cycle inflection. Higher interest rates (Articles 140/159/172/176) pressuring household credit expansion, making fintech BNPL/zero-interest products more attractive (validates product demand). However, profitability dependent on achieving scale before rate-environment deteriorates further. Valuations likely reset from 2021 peak ($2B) to more modest multiples reflecting (a) loss trajectory, (b) competitive intensity (Monzo, Starling), (c) macroeconomic headwinds (Articles 140 consumption deceleration, household savings rates under pressure from higher rates).
What Happened?
UK fintech Zilch invited investment banks to pitch for IPO roles, targeting flotation on London Stock Exchange next year. Company valued $2B in 2021 fintech boom, but peak valuation unlikely to repeat. FY2025: £10.5M loss (down from £50M prior year). Company targeting profitability by listing. 6M customers; offers cashback debit card, buy-now-pay-later, zero-interest loans. Revenue from targeted advertising on transaction data. Backers: eBay, Goldman Sachs, DMG Ventures, KKCG ($175M November deal). January: acquired Fjord Bank (Lithuania) for European banking license. Founded 2018. Competitors: Monzo (Nubank discussions), Starling, OakNorth, SumUp (Europe/UK listing planned). LSE owner LSEG courting fintech IPOs amid takeover drought.
Why It Matters?
Zilch IPO validates that UK fintech sector returning to capital markets after multiyear drought (Articles 160/163 on EM IPO activity). However, valuation reset from $2B (2021 peak) to lower multiples validates that fintech sector repriced post-boom. Loss trajectory (£50M → £10.5M) improving but still unprofitable validates dependency on achieving profitability before listing (contradicts Article 167 Anthropic model: high losses at IPO acceptable; Zilch cannot replicate $2T valuation with 5% of Anthropic’s revenue). BNPL/zero-interest product strategy validates consumer credit migration in high-rate environment (Articles 140/159/172/176): households substituting traditional bank credit with fintech alternatives. Data monetization (targeted advertising) validates Article 169 thesis on AI agents monetizing transaction data (validates Articles 165/171 on privacy/agent risks rippling into fintech). Fjord Bank acquisition validates geographic arbitrage strategy (validates Article 160 India expansion thesis applied to UK-EU fintech cross-border scaling).
What’s Next?
Monitor bank pitching outcomes and timeline: if Q1 2026 mandate announcement, validates IPO pathway clarity. Watch Zilch profitability trajectory: if FY2026 (March 2026 close) shows inflection to profit, validates IPO valuation case; if losses persist, validates valuation pressure. Track competitor IPO timelines: if Monzo/Starling announce listings ahead of Zilch, validates IPO race dynamics (may pressure valuations as investors allocate IPO capital across fintech peers). Monitor interest-rate environment: if Fed cuts (Articles 140 growth-at-risk forces pivot), reduces BNPL demand appeal (validates rate-environment dependency). Watch LSE-LSEG fintech courtship: if Zilch IPO succeeds at reasonable valuation, validates UK fintech revival; if underperforms, validates sector repricing. Finally, track household credit conditions: if consumption deceleration (Article 140) accelerates, BNPL demand could weaken (validates recession risk to fintech growth).
Affected Tickers and Coins: LSEG | GS | eBay | DMG Ventures | KKCG | Monzo | Starling | OakNorth | SumUp | Nubank
Source: Financial Times