Strong PMI Validates Economic Acceleration Against Rate Headwinds
S&P Global purchasing-managers index released Wednesday provided strongest evidence economy accelerating, not merely holding firm. Manufacturing activity registered biggest monthly increase since 2022. Service-sector activity jumped to highest level since 2021. New orders powered growth in both sectors. Report triggered biggest one-day jump in 10-year Treasury yield since Trump’s “Liberation Day” tariff announcement (April 2025). PMI report eye-opening for economists previously optimistic inflation would fall without much higher rates. But data now validates risk of private-sector demand overheating if AI capex growth persists without moderation.
Treasury Yields Hit 20-Year Highs Despite Low Inflation Expectations
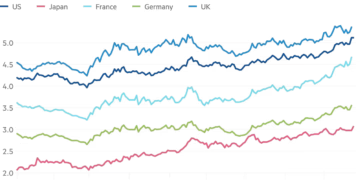
10-year Treasury yield climbed to nearly 5.2% this week—20-year highs. Breakeven inflation rate (bond market indicator of expected inflation) remains modest. Validates that yield surge NOT inflation-driven but growth-driven. Investors concerned about Fed needing to raise rates much higher than previously expected to cool potentially overheating economy. Strong economic data (hiring picked up August, layoffs stayed low, manufacturers reporting pickup) fueling speculation on additional Fed hikes beyond current expectations. Yields closely correlated to oil prices, reflecting geopolitical/inflation premium from unresolved Iran conflict (not structural inflation).
AI Investment Boom Proving Immune to Rate Pressure; Supply Chain Ripples Outward
AI-driven growth looks resistant to higher borrowing costs. Tech companies’ investments appearing unstoppable despite steep interest rates. Conventional economic brakes not slowing growth, hiring, or AI investment boom. Eric Winograd (AllianceBernstein): “Everything that gets put into building a data center has to be built somewhere.” Supply chain filtering through broader economy, broadening expansion base beyond pure AI. Validates thesis that bright AI potential returns justify continued capex even at 7% mortgage rates, 5.2% Treasury yields. Infrastructure capex rippling to construction, equipment, logistics sectors.
Mortgage Rates Hit 7% for First Time in Over a Year; Demographic Split Emerges
Mortgage rates hit 7% Thursday (first time in >1 year), capping rise that smothered home sales. Commercial landlords feeling squeeze from higher rates. But many consumers’ investment accounts lifted by soaring stock indexes (boosted by strong earnings + AI optimism). Higher interest rates benefiting one-third of US households headed by someone 65+. These older consumers not seeking mortgages—enjoying higher investment returns from money-market funds. Demographic split: younger cohort hurt by housing costs, older cohort benefiting from higher returns.
Warsh Signals More Rate Hikes Needed; Futures Pricing 100bp by End 2027
Fed raised rates for first time in three years (last week). Most officials expect at least one more hike before end of year. Warsh’s press conference language—”removed a dose of accommodation”—interpreted by investors as signaling even higher rates necessary for Fed to maintain anti-inflation grip. As economy heats up, Fed needs higher rates to sustain same anti-inflation pressure. Predominant bets in rate futures markets show expectations Fed may hike full percentage point by end 2027 (validates multiple-hike cycle, not just October). Warsh’s uncertainty (new chairman, unknown approach) adding to investor concerns on rate path.
What Happened
S&P PMI released Wednesday: manufacturing activity biggest monthly increase since 2022, services highest since 2021. Report triggered biggest 10-year yield jump since April 2025 tariff announcement. Yield climbed to nearly 5.2% (20-year high). Hiring picked back up August, layoffs stayed low, manufacturers reporting pickup. Powered by AI investment, underlying growth strong. Breakeven inflation expectations remain modest (validates growth-driven, not inflation-driven yield surge). Oil prices closely correlated to yields (geopolitical premium). Mortgage rates hit 7% (first time >1 year), smothering home sales. Commercial landlords feeling squeeze. But older households (1/3+ of population 65+) benefiting from higher investment returns. Fed raised rates last week; most officials expect at least one more before year-end. Warsh’s “removed dose of accommodation” phrase signals more hikes needed. Futures pricing ~100bp hikes by end 2027.
Why It Matters
For equity investors, economic resilience validates growth narrative despite rate headwinds. AI investment boom resisting rate pressure validates thesis that returns sufficiently bright. Older consumers (1/3+ of households) benefiting from higher rates—positive for consumer spending. For bond investors, 5.2% yields likely continue higher if growth persists. For housing sector, 7% mortgage rates + Fed hikes create headwind. For macroeconomists, risk of overheating economy if AI capex continues unabated. For Fed, challenge: if growth driven by AI capex (supply-side boost), raising rates may not cool without crushing non-AI sectors.
What’s Next
Monitor Fed October meeting; if raise rates again, validates Warsh’s signaling. Track next PMI reports; if growth continues accelerating, validates overheating risk narrative. Watch mortgage/housing data; if sales continue declining, validates rate headwind despite economic strength. Monitor oil prices; if fall below $100 (Iran resolution), it removes geopolitical premium + could ease yield pressure. Also track AI capex spending announcements; if continues accelerating, validates thesis that rates not slowing investment. Monitor Fed speakers; if Warsh/others signal higher rates needed, could trigger bond sell-off. Finally, watch older consumer spending data; if holds up despite housing headwinds, validates demographic wealth effect offsetting rate pain.
Affected Tickers & Exchanges:
SPY (S&P 500 ETF, NYSE) | QQQ (Nasdaq-100, NASDAQ) | TLT (iShares 20+ Year Treasury, NASDAQ) | IEF (iShares 7-10 Year Treasury, NASDAQ) | XHB (Homebuilders ETF, NASDAQ) | USO (Oil Fund, NYSE) | NVDA (Nvidia, NASDAQ) | AMZN (Amazon, NASDAQ) | MSFT (Microsoft, NASDAQ) | GOOGL (Alphabet, NASDAQ)
Source: Wall Street Journal