Powered by LumidaWealth.com
Lumida News
  • Home
  • EarningsNEW
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Macro
    • Markets
    • Real Estate
  • Lifestyle
    • Family Office
    • Health and Longevity
  • Themes
    • Aging & Longevity
    • AI
    • CRE
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
  • About Us
No Result
View All Result
Lumida News
No Result
View All Result
  • Lumida Wealth
  • Lumida Ledger
  • LUMIDA ETF
  • About Us
Home News Equities

Gold Fields Mounts ‘Charm Offensive’ to Woo Northern Star Shareholders; A$39bn Bid Rejected but Elliott Activism, Trading Discount Signal Deal Momentum May Resume

by Team Lumida
October 14, 2026
in Equities
Reading Time: 10 mins read
A A
0
Gold Fields Mounts ‘Charm Offensive’ to Woo Northern Star Shareholders; A$39bn Bid Rejected but Elliott Activism, Trading Discount Signal Deal Momentum May Resume
Share on TelegramShare on TwitterShare on FacebookShare on LinkedinShare on Whatsapp
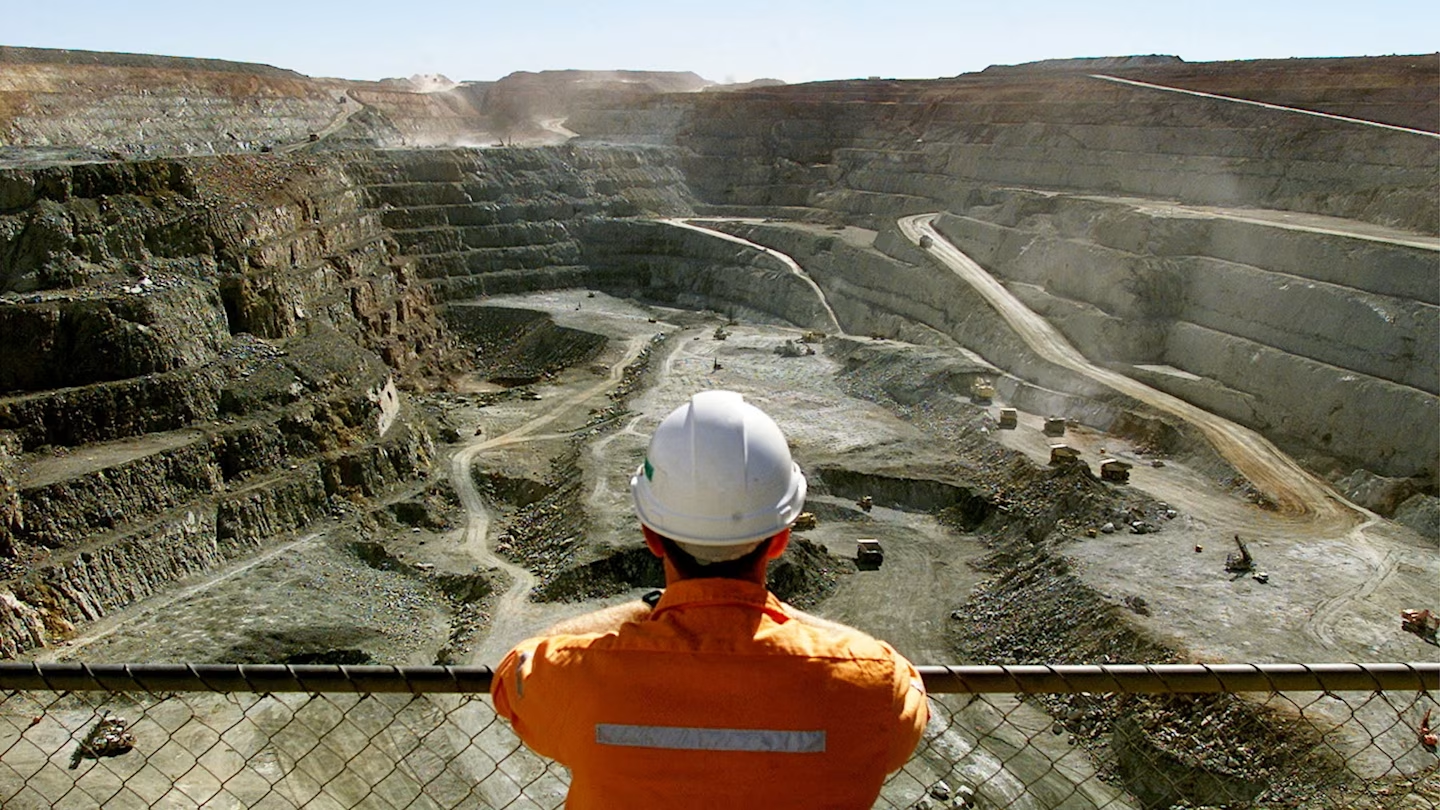
  • Gold Fields, South Africa’s largest gold miner, has embarked on a “charm offensive” in Australia, with CEO Mike Fraser traveling to Perth, Sydney, and Melbourne to meet shareholders and make the case for its A$39 billion (approximately $27 billion USD) takeover bid for Northern Star Resources. The bid, rejected by Northern Star’s board last month, would create the world’s second-largest gold miner with a combined market value of approximately $56 billion. Fraser told the Financial Times that shareholders he met were receptive to the combination, particularly around the prospect of creating a “Western Australian powerhouse in gold production.” The language matters: Gold Fields is not just pitching financial engineering or cost-cutting synergies. It’s pitching a regional consolidation story—combining two of Australia’s largest gold operators into a single, globally significant producer. For Australian institutional investors with ESG and regional investment mandates, that narrative has appeal. But the broader dynamic is more subtle: Gold Fields is bypassing Northern Star’s board and going directly to shareholders, a classic M&A tactic when management is hostile but the shareholder case is compelling. Fraser said Gold Fields had been courting Northern Star management for a year without meaningful engagement, suggesting the board has been unreceptive to combination discussions. The public nature of the current “charm offensive” reflects a strategic shift: with Elliott Management’s activist stake now pushing for board engagement, and Northern Star’s share price trading at a discount to the implied bid value, the dynamics have shifted in Gold Fields’ favor.
  • The share price speaks volumes. Northern Star closed at A$24.91 on the session—meaningfully below the A$27 per share implied by Gold Fields’ A$39 billion valuation. That discount (approximately 7.7%) is material and signals market skepticism about Northern Star’s standalone prospects or skepticism about deal completion risk. In M&A terms, this discount is significant. If markets believed Northern Star was worth more than A$27, the stock would trade closer to the bid (or above it if bidders were competing). Instead, the 7.7% discount reflects: (1) market doubt about Northern Star’s ability to execute growth projects independently, (2) market assessment that Gold Fields’ bid is the most likely outcome but faces board/management resistance, or (3) market pricing in deal failure risk. Fraser explicitly cited Northern Star’s execution risk, noting “We see a lot of risk ahead for Northern Star as they execute their growth projects,” particularly the Hemi development in the Pilbara region. That comment is surgical: Fraser is not attacking Northern Star’s assets or deposit quality. He’s questioning management’s ability to execute a complex pipeline of projects on time and budget—a legitimate concern for growth-dependent companies. Northern Star has already taken a series of profit warnings, supporting that narrative. For shareholders, the discount to bid price is an arbitrage: either the deal completes at A$27 (upside), or Northern Star executes standalone and justifies a higher valuation (but facing execution risk). Markets are pricing low conviction on the standalone case.
  • Elliott Management’s activist involvement is the game-changer. The activist investor has taken a stake in Northern Star and is pushing the board to engage with Gold Fields. Elliott doesn’t own Northern Star outright, but its stake and public pressure carry significant sway. A person familiar with Elliott’s position told the Financial Times that the firm would evaluate any proposal “on its merits” and expected Northern Star’s board to do the same. That language is diplomatic but pointed: Elliott is saying Gold Fields’ offer deserves serious board consideration, which implicitly criticizes Northern Star’s previous rejection. Northern Star’s new CEO, Suresh Vadnagra (ex-Glencore executive who just took office this month), is due to provide his first public comments next week when the company reports quarterly results. That timing is critical: Vadnagra could use the earnings call to signal openness to talks, or he could reaffirm Northern Star’s preference to pursue standalone strategy. The fact that Elliott is pushing for engagement and the market is skeptical of standalone value creates a window where Vadnagra could credibly pivot toward negotiations. Activism works when it provides political cover for management to shift positions—Vadnagra can credibly say Elliott demanded engagement and market dynamics support discussions. Northern Star’s chair Michael Chaney told the FT that the board wants to act in shareholders’ best interests and would engage “with parties on proposals that represent value above what we believe Northern Star can generate as a standalone company.” Notably, Chaney said Gold Fields’ proposal was “not in that category”—but that statement was made before Vadnagra took office and before Elliott went public. Those dynamics have shifted.
  • Gold Fields’ strategic rationale is compelling: $5 billion in run-rate synergies by combining operations in the Kalgoorlie region of Western Australia. That’s not abstract finance; it’s geographic arbitrage. The two companies have overlapping mills, processing infrastructure, and mine footprints. Combining them eliminates redundancy and reduces operating costs. Fraser notes “it will be very hard for anyone else to recreate that value,” which is true—Agnico Eagle or other potential bidders would get a smaller synergy pool because they lack the same footprint. That creates a competitive moat around Gold Fields’ offer. For the market, the key question is whether $5 billion in synergies justifies a premium to Northern Star’s standalone value. If Northern Star trades at A$24.91 and represents a market cap of roughly A$42 billion, then Gold Fields is paying a ~7% premium for standalone value plus synergies. That’s a reasonable structural arbitrage. The discount on the share price relative to the offer suggests markets believe some of those synergies are real but there’s deal risk (management resistance, regulatory concerns, execution risk on integration). Fraser frames the timeline as “early days” and wants resolution “in the not-too-distant future,” which is M&A speak for “we’re willing to walk if this drags on indefinitely, but we’re patient enough to wait for Northern Star’s new management and activist pressure to create an opening.”

What Happened?

Gold Fields, South Africa’s largest gold producer, has launched a direct appeal to Northern Star Resources shareholders to support its A$39 billion takeover bid, after the Australian miner’s board rejected the offer last month. CEO Mike Fraser traveled to Perth, Sydney, and Melbourne this week to meet with major shareholders and institutional investors, making the case for a combined company that would create the world’s second-largest gold miner with a market value of approximately $56 billion. Fraser emphasized the strategic benefits of creating a “Western Australian powerhouse in gold production” by combining the two companies’ overlapping operations in the Kalgoorlie region. Gold Fields claims it can generate approximately $5 billion in annual run-rate synergies through elimination of redundant infrastructure and mill processing. Northern Star’s board, led by Chair Michael Chaney, has maintained that Gold Fields’ offer undervalues the company’s standalone growth potential, particularly regarding the Hemi development project in the Pilbara. However, Northern Star’s share price closed at A$24.91, approximately 7.7% below the A$27 per share implied by Gold Fields’ bid, signaling market skepticism about standalone value or deal execution concerns. Elliott Management, an activist investor with a stake in Northern Star, has publicly called on the board to engage with Gold Fields. Northern Star appointed a new CEO, Suresh Vadnagra (former Glencore executive), this month; he is scheduled to provide his first public comments as leader during the company’s quarterly earnings report next week. Fraser indicated the process is in “early days” but expects resolution “in the not-too-distant future,” while noting significant execution risk ahead for Northern Star’s growth projects.

Why It Matters?

The Gold Fields-Northern Star bid represents a critical test of whether M&A markets can consolidate strategic assets when management and shareholders have misaligned incentives. Northern Star’s board has rejected the offer as undervaluing the company, but the 7.7% discount between Northern Star’s trading price and the implied bid price signals that the market does not fully price in Northern Star’s standalone growth potential. This arbitrage reflects either (1) market doubt about management’s ability to execute complex growth projects, (2) assignment of meaningful deal completion probability (with Gold Fields holding the upper hand), or (3) both. Elliott Management’s activist involvement raises the probability that Northern Star will eventually engage with Gold Fields, particularly under new CEO Suresh Vadnagra, who can credibly pivot toward negotiations without appearing to capitulate to the previous board’s resistance. For Gold Fields, the $5 billion synergy case is strong: two adjacent gold operations with overlapping mills and infrastructure create genuine consolidation economics that would be difficult for other bidders to replicate. For the market, this deal is a referendum on whether Australian mining assets—particularly constrained by execution risk on growth projects—will consolidate or remain standalone. If Northern Star accepts or enters negotiations, it validates the activist thesis that standalone strategies face headwinds. If Northern Star successfully resists and executes Hemi on schedule and budget, it validates the board’s confidence in standalone value. The share price discount suggests markets assign higher probability to the former.

What’s Next?

Northern Star’s quarterly earnings report next week (timing TBD) is the critical near-term catalyst. Monitor CEO Suresh Vadnagra’s commentary carefully for any signals of openness to board-level engagement with Gold Fields. Language about “reviewing strategic options” or “engaging with interested parties” would signal a shift from prior management’s hostile stance. Conversely, aggressive defensive language would suggest continued resistance. Watch for Northern Star board composition or strategic committee changes in coming weeks. If the board brings on independent directors or appoints an M&A-focused committee, it signals potential openness to transactions. If board membership remains static, it suggests confidence in standalone strategy. Monitor Northern Star’s execution on Hemi project milestones and cost estimates. Any project slippage or cost overruns would validate Fraser’s execution risk commentary and increase deal probability. Strong project progress would validate the board’s standalone thesis. Track Elliott Management’s public communications. If Elliott pushes harder for engagement or hints at board contests, it accelerates deal momentum. If Elliott remains quiet, it suggests the activist believes internal pressure (new CEO, market dynamics) is sufficient. Monitor for other bidder interest, particularly from Agnico Eagle, which was mentioned in FT commentary as a potential alternative. If Agnico or other majors enter the bidding, it could reignite competitive tension and drive Northern Star price higher. If no other bidders emerge, it strengthens Gold Fields’ position. Finally, watch Northern Star’s share price closely relative to the A$27 bid-implied level. If the discount narrows, it suggests markets are pricing in higher deal probability. If the discount widens, it suggests deal skepticism has increased.

Affected Tickers and Coins: GFI (Gold Fields NYSE) | NST (Northern Star ASX) | AEM (Agnico Eagle; potential alternative bidder)

Source: Financial Times
Previous Post

Eurozone Bond Yields Open Lower Ahead of U.S. CPI Data; Markets Assign 78% Probability to Fed Hold Oct. 28; German Bund, French OAT Relief After Weeks of Decline

Next Post

Olympus Shares Plunge 13.5% on Expanded FDA Warning Letter; Systemic Quality Issues Across 6 Factories Signal Years-Long Resolution; Private Equity Circles Distressed Asset

Recommended For You

Olympus Shares Plunge 13.5% on Expanded FDA Warning Letter; Systemic Quality Issues Across 6 Factories Signal Years-Long Resolution; Private Equity Circles Distressed Asset

by Team Lumida
2 hours ago
Olympus Shares Plunge 13.5% on Expanded FDA Warning Letter; Systemic Quality Issues Across 6 Factories Signal Years-Long Resolution; Private Equity Circles Distressed Asset

Olympus -13.5% (intraday -16.5%) on FDA warning letter citing quality management system failures across 6 factories (US, Japan, Europe). CEO White's PE-style turnaround (job cuts, portfolio simplification) failing...

Read more

The Administration Will Fund a Refinery Expansion Under the Defense Production Act, While US Refiners Run at 92.5% of Capacity

by Team Lumida
16 hours ago
The Administration Will Fund a Refinery Expansion Under the Defense Production Act, While US Refiners Run at 92.5% of Capacity

Capacity is not the binding constraint. Refiners are already running below it because of margins and maintenance.

Read more

Switzerland Is Designing a Bank Tax That Applies to Exactly One Bank, Because UBS Absorbed the Only Other Candidate

by Team Lumida
17 hours ago
Switzerland Is Designing a Bank Tax That Applies to Exactly One Bank, Because UBS Absorbed the Only Other Candidate

Lenders would pay a fee for a liquidity backstop they cannot claim, provided by a creditor that ranks ahead of them.

Read more

A $72 Billion Conglomerate Is Slowing Its AI Spending Because Its Businesses Have No Common Use Case

by Team Lumida
18 hours ago
Senate Stock Trading Ban Fails 53-47 on a Bill That Would Have Left Existing Holdings, Private Shares and Prediction Markets Untouched

Kumar Mangalam Birla says there is no need to act out of FOMO, while hyperscalers raise tens of billions in debt for the same technology.

Read more

S&P 500 Futures Mixed Ahead of Bank Earnings as KOSPI Slides Below 6,000; JPMorgan, Goldman, Citi, Wells Fargo Report Before Open While Nasdaq Futures Lag on Memory Stock Weakness

by Team Lumida
1 day ago
S&P 500 Futures Mixed Ahead of Bank Earnings as KOSPI Slides Below 6,000; JPMorgan, Goldman, Citi, Wells Fargo Report Before Open While Nasdaq Futures Lag on Memory Stock Weakness

S&P 500 futures flat; Nasdaq-100 -0.58%; Dow +0.52%. JPM, GS, C, WFC, UNH report Tue AM. FactSet: 30% EPS growth expected. KOSPI -5.46% (below 6K; lowest July 31)....

Read more

Accenture’s AI Paradox: $130 Billion Valuation Hinges on Survival Question as Organic Growth Faces Deflationary Pressure; Investor Day Must Prove Consulting Model Survives

by Team Lumida
1 day ago
Accenture’s AI Paradox: $130 Billion Valuation Hinges on Survival Question as Organic Growth Faces Deflationary Pressure; Investor Day Must Prove Consulting Model Survives

Accenture shares: steepest fall + 2nd-largest gain in 25 years (3 months). Valuation $76B→$130B. Organic growth weak (~2% FY2026 forecasted decline). Revenue per employee key metric. Headcount 814K...

Read more

Banks Enter Earnings in Correction With Analysts Expecting Steady Credit, Days After the Fed Reported the Worst Debt Burdens Since 2010

by Team Lumida
2 days ago
Banks Enter Earnings in Correction With Analysts Expecting Steady Credit, Days After the Fed Reported the Worst Debt Burdens Since 2010

Trading revenue near $19 billion is the easy part. What executives say about the consumer is the number that matters.

Read more

Stellantis Rules Out a Breakup While Its Shares Fall 60%, the Worst in the Stoxx 600

by Team Lumida
2 days ago
Stellantis Rules Out a Breakup While Its Shares Fall 60%, the Worst in the Stoxx 600

The real strategy is Chinese technology filling European plants, announced as carmakers lobby to cap Chinese imports.

Read more

OPay Locks In $200 Million Privately Before Its New York IPO, Days After Firmus Showed What Happens Without It

by Team Lumida
2 days ago
OPay Locks In $200 Million Privately Before Its New York IPO, Days After Firmus Showed What Happens Without It

More than 50 million monthly active users, and the listing will set a valuation benchmark for African venture portfolios.

Read more

Google’s $180 Fitbit Edge Comes With a $100-a-Year Subscription, So the Service Outruns the Hardware Inside Two Years

by Team Lumida
2 days ago
Google’s $180 Fitbit Edge Comes With a $100-a-Year Subscription, So the Service Outruns the Hardware Inside Two Years

It also tracks changes in insulin resistance, pushing consumer wearables toward clinically adjacent data.

Read more
Next Post
Olympus Shares Plunge 13.5% on Expanded FDA Warning Letter; Systemic Quality Issues Across 6 Factories Signal Years-Long Resolution; Private Equity Circles Distressed Asset

Olympus Shares Plunge 13.5% on Expanded FDA Warning Letter; Systemic Quality Issues Across 6 Factories Signal Years-Long Resolution; Private Equity Circles Distressed Asset

ASML Raises 2026 Guidance to €44-45bn; Cannot Fully Meet 2027-2028 Demand; Multi-Year Forward Orders Extend to 2029-2030, Validating Sustained AI Capex Cycle

ASML Raises 2026 Guidance to €44-45bn; Cannot Fully Meet 2027-2028 Demand; Multi-Year Forward Orders Extend to 2029-2030, Validating Sustained AI Capex Cycle

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Related News

Retailers Rush Back Into Brick-and-Mortar as Vacancies Tighten and Consumer Spending Holds Up

Retailers Rush Back Into Brick-and-Mortar as Vacancies Tighten and Consumer Spending Holds Up

December 3, 2025
UPS $UPS Q2 2024 Results

UPS $UPS Q2 2024 Results

July 24, 2024
a roll of toilet paper

Fed’s Balancing Act: Inflation vs. Unemployment – Key Insights for Investors

June 25, 2024

Subscribe to Lumida Ledger

Browse by Category

  • Lifestyle
    • Family Office
    • Health and Longevity
    • Legacy
    • Next Gen Wealth
    • Trust, Tax, and Estate
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Latest
    • Macro
    • Markets
    • Real Estate
  • Opinions
    • Investing Philosophy
    • Op-Ed
  • Research
    • Trackers
  • Themes
    • Aging & Longevity
    • AI
    • Biotech
    • CRE
    • Cybersecurity
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
    • Software
Facebook Twitter Instagram Youtube TikTok LinkedIn
Lumida News

Premium insights to help you invest beyond the ordinary. Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser

CATEGORIES

  • Aging & Longevity
  • AI
  • Alt Assets
  • Biotech
  • CRE
  • Crypto
  • Cybersecurity
  • Digital Assets
  • Equities
  • Family Office
  • Health and Longevity
  • Investing Philosophy
  • Latest
  • Legacy
  • Legacy Brands
  • Lifestyle
  • Macro
  • Markets
  • News
  • Next Gen Wealth
  • Nuclear Renaissance
  • Op-Ed
  • Private Credit
  • Real Estate
  • Software
  • Themes
  • Trackers
  • Trust, Tax, and Estate

BROWSE BY TAG

AI AI chips Amazon Apple Artificial Intelligence Banking Bitcoin China Commercial Real Estate CPI Crypto data centers Donald Trump EARNINGS ELON MUSK ETF Ethereum Federal Reserve financial services generative AI Goldman Sachs Google India Inflation Intel Interest Rates Investment Strategy Japan Jerome Powell JPMorgan Markets Meta Microsoft Nasdaq Nvidia OpenAI private equity S&P 500 SEC stock market Tech Stocks tesla Trump Wells Fargo Whale Watch

© 2025 Lumida Wealth Management LLC is an SEC registered investment adviser. Privacy Policy. Cookies Policy.
Disclaimer Important Information This site is for informational purposes only. Information presented on this site does not constitute as investment advice.

Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser. SEC registration does not constitute an endorsement of the firm by the Commission nor does it indicate that the adviser has attained a particular level of skill or ability.

Lumida's website (referred to herein as the "Website") is limited to the dissemination of general information pertaining to its advisory services, together with access to additional investment-related information, publications, and links. Accordingly, the publication of the Website on the Internet should not be construed by any client and/or prospective client Lumida’s solicitation to effect, or attempt to effect transactions in securities, or the rendering of personalized investment advice for compensation, over the Internet.

Any subsequent, direct communication by Lumida with a prospective client will be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides.

‍Lead Capture Forms: By submitting your contact information in the forms on this site, you are not obligated to invest in Lumida's product or services.
‍Address: Lumida Wealth Management, 25 W 39th Street Suite 700, New York, NY 10018

No Result
View All Result
  • Home
  • Earnings
  • News
    • Alt Assets
    • Crypto
    • Equities
    • Macro
    • Markets
    • Real Estate
  • Lifestyle
    • Family Office
    • Health and Longevity
  • Themes
    • Aging & Longevity
    • AI
    • CRE
    • Digital Assets
    • Legacy Brands
    • Nuclear Renaissance
    • Private Credit
  • About Us

© 2025 Lumida Wealth Management LLC is an SEC registered investment adviser. Privacy Policy. Cookies Policy.
Disclaimer Important Information This site is for informational purposes only. Information presented on this site does not constitute as investment advice.

Lumida Wealth Management LLC (‘Lumida”) is an SEC registered investment adviser. SEC registration does not constitute an endorsement of the firm by the Commission nor does it indicate that the adviser has attained a particular level of skill or ability.

Lumida's website (referred to herein as the "Website") is limited to the dissemination of general information pertaining to its advisory services, together with access to additional investment-related information, publications, and links. Accordingly, the publication of the Website on the Internet should not be construed by any client and/or prospective client Lumida’s solicitation to effect, or attempt to effect transactions in securities, or the rendering of personalized investment advice for compensation, over the Internet.

Any subsequent, direct communication by Lumida with a prospective client will be conducted by a representative that is either registered or qualifies for an exemption or exclusion from registration in the state where the prospective client resides.

‍Lead Capture Forms: By submitting your contact information in the forms on this site, you are not obligated to invest in Lumida's product or services.
‍Address: Lumida Wealth Management, 25 W 39th Street Suite 700, New York, NY 10018